Which business structure truly suits your goals: one that keeps admin light, or one that helps you scale with investors?
This short guide helps founders make a practical choice between two common company options in the local market. It focuses on what matters in day-to-day operations: cost, compliance, tax and how easy it is to raise capital.
Expect an actionable comparison that goes beyond legal definitions. You will learn which structure offers flexibility for small teams and which one supports growth and fundraising. The guide explains why these differences affect both short-term tasks and long-term outcomes.
Singapore’s regulator, ACRA, shapes the compliance landscape, so picking the right option early can prevent costly restructuring later. Use this article to stop second-guessing and move from research to execution with confidence.
Key Takeaways
- Choose based on how you operate today and where you want to grow.
- Lower admin and flexibility suit small professional teams.
- Formal company form is better for fundraising and scaling.
- Tax, liability and compliance are core decision factors.
- Picking the right option early avoids costly restructuring later.
Why your choice of business structure in Singapore matters in today’s market
A business structure shapes practical decisions — from contracts and banking to tax reporting.
The legal entity you choose determines how you contract with clients, how you record income, and how you meet annual filing obligations with ACRA. These mechanics change daily workflows for founders and teams.
Risk control matters: the right form separates business assets from personal exposure in most cases. That separation can reduce personal liability for business debts, but it does not remove responsibility for misconduct or negligence.
Compliance expectations also shape overhead. Greater regulatory duties take founder time away from delivery and sales. For lean teams, lower admin costs can be a strategic advantage.
Your chosen structure also affects credibility with banks, clients and counterparties. Lenders and investors often prefer entities with clearer governance and record-keeping when assessing risk.
- Structure influences hiring, adding owners and preparing for external investment.
- Early choice can save time and avoid costly restructuring later.
In short, matching your operational model to the ACRA requirements for each entity type will reduce surprises as your businesses pursue growth.
What is a Limited Liability Partnership (LLP)?
A limited liability partnership gives two or more professionals a single business identity while keeping day-to-day management simple.
Separate legal entity status means the partnership can hold property, sign contracts and carry on business in its own name. In practice this lets the entity sue or be sued and keeps business assets distinct from partners’ personal assets.
How partners run the business
Partners manage operations directly and tailor decision-making through an LLP agreement. This setup avoids a board structure and keeps control closer to those doing the work.
Profit sharing and liability boundaries
Profit splits are flexible and need not match capital contributions. That supports bespoke commercial terms between partners.
For liability, the entity normally meets business debts, offering limited liability protection for personal assets. However, a partner remains personally liable for their own wrongful acts or negligence.
| Feature | Practical effect | Who benefits |
|---|---|---|
| Separate legal entity | Entity holds contracts and assets | Consultants, accountants, lawyers |
| Management | Partners run the business directly | Small teams wanting control |
| Profit sharing | Flexible ratios agreed in writing | Commercially bespoke arrangements |
| Fundraising | No share issuance; limited options | Teams not planning equity fundraising |
What is a Private Limited Company (Pte Ltd)?
A private limited company offers founders a formal corporate shell that separates ownership from day-to-day management.
Definition and legal status: A private limited company is a limited company that is a separate legal entity from its shareholders. This means the company can own assets, sign contracts and take legal action in its own name.
How liability protection works: Shareholders usually face limited liability. Their financial risk is generally confined to the capital invested in shares rather than personal assets.
How a Pte Ltd operates independently from its shareholders
The company continues to trade even when shares change hands. Directors run operations and the company signs agreements as the legal party.
Regulatory requirements include appointing at least one local director and a corporate secretary. These roles help maintain governance and compliance.
Why Pte Ltds are often seen as more credible for growth
Structured governance and transferable shares make a Pte Ltd familiar to investors and banks. That familiarity supports fundraising and exit planning.
When founders choose this route: startups aiming for external investment or bank financing often prefer the predictability and accountability that a Pte Ltd provides.
| Feature | Practical effect | Who benefits | Notes |
|---|---|---|---|
| Separate legal entity | Company holds assets and contracts | Shareholders, creditors | Perpetual succession supports stability |
| Limited liability | Risk usually limited to share capital | Owners and minority investors | Personal assets generally protected |
| Share transferability | Easier to bring in investment | Founders, external investors | Enables partial exits and cap table changes |
| Governance requirements | Directors and company secretary needed | Regulators, banks | Higher admin but stronger credibility |
llp vs private limited singapore: the key differences at a glance
Use this quick comparison to see how ownership, tax and compliance stack up between the two common structures.
Ownership and control
Partners run the business directly and set internal terms by agreement. Control is flexible and informal.
Shareholders own the company, while directors handle management. Ownership and control are separate, which helps governance.
Liability protection
Both structures provide protection for business debts at entity level. Personal exposure is limited unless a person commits wrongdoing or negligence.
Practical point: partners are generally not liable for other partners’ misconduct, but personal acts can create personal liability.
Tax treatment
One option uses pass‑through taxation: profits flow to owners and are taxed at personal rates.
The other pays corporate tax (headline rate 17%) with possible exemptions and incentives that lower effective tax rates.
Compliance requirements
One form has lower ongoing admin: no AGMs, and a simpler annual declaration is required.
The corporate form requires annual returns, audited or unaudited financial statements depending on size, and more formal record‑keeping.
Fundraising and transferability
Raising capital by issuing shares is typically only available to companies, making them easier to fund and more familiar to banks and investors.
Changing owners in a partnership often needs agreement from existing partners and can be administratively heavier.
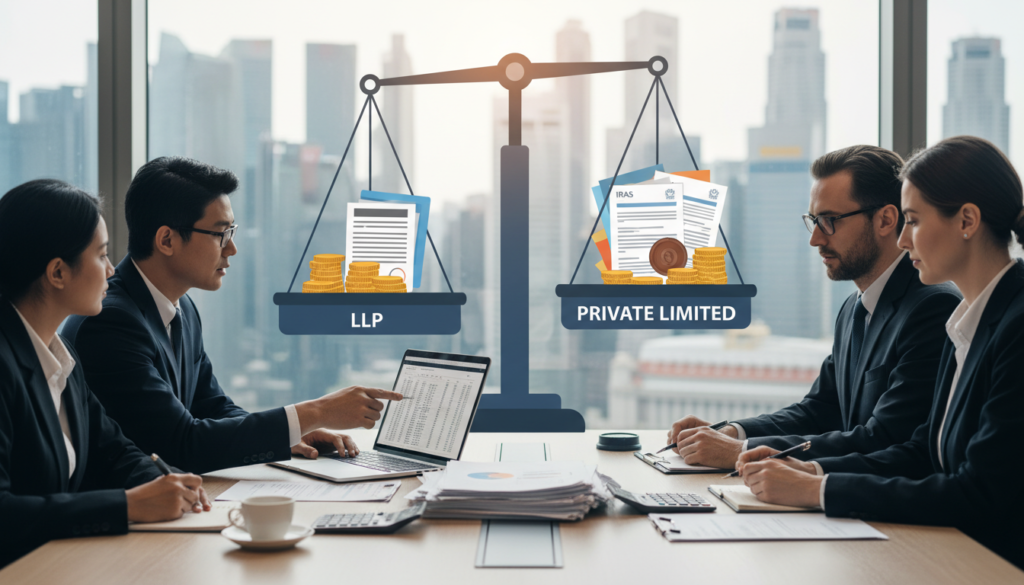
| Area | Partnership model | Company model |
|---|---|---|
| Ownership | Partners manage and own directly | Shareholders own; directors manage |
| Liability | Entity meets business debts; personal liability for own misconduct | Limited to share capital in most cases; personal acts still liable |
| Tax | Pass‑through to owners; taxed at personal rates | Corporate tax (17%) with reliefs and incentives |
| Compliance | Lower admin; annual declaration and records | Higher admin; annual returns and financial statements |
| Fundraising | No share issuance; partner consent needed for changes | Can issue shares; easier to bring in investors |
Taxation and tax benefits: personal tax rates vs corporate tax rates
How your profits are taxed can change whether a structure feels affordable or costly in the long run.
How partnership profits flow to partners
The partnership itself is generally not taxed like a company. Instead, profits pass through to each partner and are taxed in their hands.
That means partners pay personal tax on their share of profits. The final burden depends on each partner’s other income and marginal personal tax rate.
Corporate tax and why the headline rate may be misleading
A company pays corporate tax at a headline tax rate of 17%.
Effective tax rates can be lower after allowable deductions, start‑up reliefs and incentives. This often makes the corporate route more attractive for retained profits and reinvestment.
When tax exemptions and incentives favour incorporation
Tax exemptions and incentives can tilt the choice towards forming a company when the plan is to grow and keep profits in the business.
Decisions should weigh how founders will withdraw money — salary, dividends or drawings — and the business’s profit profile.
| Aspect | Partnership model | Company model |
|---|---|---|
| Who pays tax | Partners pay personal tax on share | Entity pays corporate tax; shareholders taxed on dividends |
| Typical headline rate | Personal tax rates (varies by income) | Corporate tax rate 17% |
| When it helps | Small teams taking profits now | Businesses reinvesting earnings for growth |
Practical tip: read a short guide to entity choice for tax and growth strategies at LLP vs Pte Ltd guide.
Compliance requirements and ongoing admin in Singapore
Operational overhead is as much about repeating compliance tasks each year as it is about the one‑time act of incorporation.
Why compliance is ongoing: meeting compliance requirements is an annual commitment. Yearly filings and record maintenance influence how much time and money founders must allocate to administration rather than core work.
Obligations for partnerships
Partnership entities have fewer formal duties. They file a simple annual declaration and must keep accurate records of transactions and accounts.
Maintaining clear books is essential. Good records make audits, tax reporting and any future restructuring smoother.
Company obligations and governance
A company faces a fuller slate of compliance requirements. These include annual returns, preparation of financial statements, and maintenance of statutory registers.
Governance expectations — meetings, minutes and transparency — add administrative overhead but also build credibility with banks and investors.
Local appointments and the secretary role
A company must appoint at least one resident director and a corporate secretary. The secretary supports filings, corporate governance and statutory compliance.
Foreign founders should budget for professional secretarial and accounting support. Outsourcing reduces risk and helps the team focus on growth.
| Area | Partnership model | Company model |
|---|---|---|
| Annual filing | Simple annual declaration | Annual returns and financial statements |
| Records | Maintain accurate transaction records | Statutory registers and minutes |
| Local roles | No resident director requirement | Must appoint resident director and secretary |
Incorporation requirements and setup costs under ACRA
Setting up an entity begins with a clear checklist: owners, roles, capital and an official address.
ACRA oversees incorporation and requires specific documents and appointments before you file. Prepare identification, an agreed structure, and a local address to avoid delays.
Minimum owners and local roles
Minimum owners: a partnership form needs at least two partners, while a pte ltd can be incorporated by a single shareholder. This makes the company path friendlier for solo founders.
Local roles: a partnership must appoint at least one local manager. A pte ltd must have at least one resident director and a corporate secretary. These choices affect dependency and service costs.
Capital and registered address basics
Paid‑up capital for a company can start at SGD1, which keeps initial capital requirements low. Capital in a partnership is agreed between partners and recorded in the partnership agreement.
Both entity types must maintain a registered Singapore business address for official correspondence and service of notices.
Typical registration fees
Current ACRA filing fees are S$115 for a partnership registration and S$315 for a pte ltd incorporation. Professional service fees are separate and vary by provider.
| Requirement | Partnership model | Pte Ltd | Typical fee |
|---|---|---|---|
| Minimum owners | At least 2 partners | One shareholder possible | — |
| Local roles | At least 1 local manager | One resident director + company secretary | May add service costs |
| Capital | Agreed between partners | Minimum paid‑up capital SGD1 | Flexible |
| ACRA registration fee | Registration S$115 | Registration S$315 | Professional fees extra |
Practical note: setup costs matter, but founders should weigh them against long‑term compliance, growth plans and the roles they must appoint.
Liability protection and business risk exposure
Understanding what “limited liability” actually covers helps you avoid surprises if a claim arises.
What limited liability covers: for companies, creditors normally claim against the business and not the shareholders’ personal assets. Shareholders typically risk only the capital they paid for shares. For a partnership, business creditors can pursue the entity first, not partners’ private property, except where partners are personally liable for specific obligations.
When partners can be personally liable
- Partners remain personally liable for their own wrongful acts or professional negligence.
- They are generally protected from other partners’ misconduct, but not from claims tied to their personal conduct.
Wider risk and continuity: contractual disputes and professional negligence create exposures beyond simple debt. Insurance, tight contracts and robust internal controls still matter.
Perpetual succession and continuity: companies usually continue regardless of changes in ownership, supporting long‑term contracts. A partnership’s continuity depends on the partnership agreement and statute, so plan for exits, death and withdrawal in writing.
| Risk area | Practical effect | What to do |
|---|---|---|
| Creditors | Claim the business first | Keep clear records; separate accounts |
| Professional negligence | Individual may be personally liable | Carry professional indemnity insurance |
| Continuity | Company: usually perpetual; Partnership: depends | Draft continuity and exit clauses |
Raising capital, attracting investors, and planning for growth
A clear equity framework makes it simpler to bring in capital and align incentives.
Issuing shares and why pte ltds are easier to fund
Share issuance lets a pte ltd sell equity to new or existing investors. This supports staged rounds and gives a clear record of who owns what.
Investors favour structures where ownership can be allocated, diluted or transferred without complex renegotiation.
Practical benefits:
- Structured rounds speed up investment decisions.
- Equity incentives help hire senior staff and retain talent during growth.
- Clear governance reassures banks and institutional investors.
Why partnerships may feel less “institutional” to banks and investors
Partnerships typically raise funds via partner contributions or debt. They cannot issue shares, which limits outside investor participation.
This can make such entities seem less established for large-scale expansion. As funding rounds and stakeholder complexity increase, corporate secretarial, accounting and tax services become essential.
How to choose between an LLP and a Pte Ltd for your Singapore business goals
Start with your 12–36 month plan: this clarifies whether simplicity or scale matters most.
Decision framework to guide your choice
Map four items: how you will earn revenue, how you will manage risk, how founders will withdraw funds, and how quickly you expect to scale.
Use that map to weigh short‑term convenience against long‑term fundraising and hiring needs.
Best-fit scenarios for a limited liability partnership
The limited liability partnership suits small professional teams that want flexible management, bespoke profit splits and lower admin. It keeps day‑to‑day control close to the partners and reduces formal filing tasks.
Best-fit scenarios for a pte ltd
A pte ltd works better for founders who plan to hire, raise external capital or serve larger corporate clients. A private limited company gives clearer equity mechanics, stronger investor confidence and a governance framework for growth.
When switching later may make sense — and the likely costs
Conversion is possible but can be disruptive. Expect new agreements, asset transfers, contract novations and tax checks. These create professional fees and delay, so plan ahead if growth is likely.
When to speak with a corporate service provider or legal counsel
Seek advice early if you are a foreign founder, have complex ownership splits, regulated activities or imminent investor talks. Professional services and legal counsel reduce risk and improve fundraising readiness.
| Fast check | Which helps | Why |
|---|---|---|
| Need simple profit draws | limited liability partnership | Flexible splits; lower admin |
| Need fundraising and hires | pte ltd | Shares, governance and investor confidence |
| Unsure but may scale | Talk to services or counsel | Plan structure and avoid costly rework |
Conclusion
Prioritise the outcomes you need in the next 12–36 months when choosing an entity.
In short: one option gives flexibility and low admin, while the other supports scale, investor confidence and structured governance. Balance tax implications with the compliance requirements and the level of risk you can accept.
Both forms offer limited liability in practice, but partners remain personally responsible for their own misconduct or negligence. That reality should shape your insurance and contract decisions.
Choose based on upcoming milestones — first hires, bank finance or investor talks — not only on current size. Shortlist priorities, map them to each setup’s traits, and get professional advice if your ownership or capital plans are complex.
FAQ
What are the main differences between a limited liability partnership and a private limited company in Singapore?
How does liability protection differ between the two structures?
Which structure offers better tax outcomes?
What are the compliance requirements for both entities?
How do ownership and control work in each form?
Which structure is easier for raising capital?
What are the incorporation requirements and typical setup costs?
When can partners or directors be personally liable?
Are there specific roles that must be appointed for a private company?
How do tax incentives and exemptions affect the choice?
Which business types are best suited to a partnership?
Which situations favour forming a private company?
Can a business change from a partnership to a private company later?
What ongoing administrative tasks should founders expect?
When should I consult a corporate service provider or legal adviser?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.