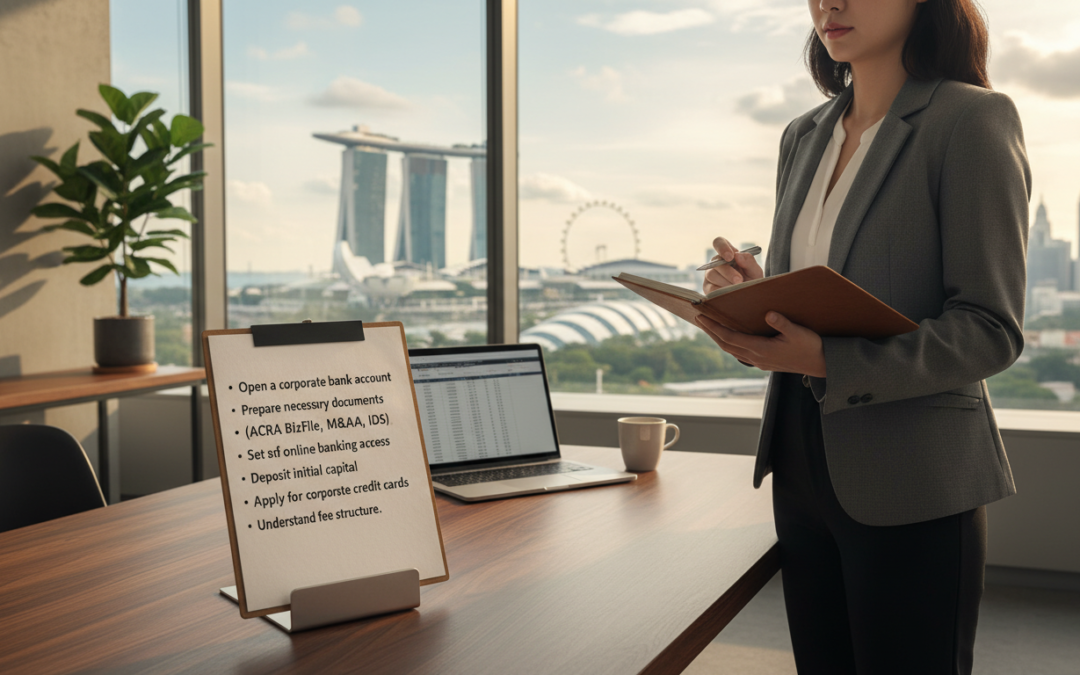
Have you prepared the precise first moves that make your new venture ready to trade and grow?
This short guide defines the exact setup actions a new company completes in its first weeks so it can transact cleanly and comply with local rules. It explains practical controls, recordkeeping and the items banks expect to see on day one.
Expect a Singapore-focused sequence covering account opening, authorised signatories, tools activation and the deposit of share capital. The aim is clear: get the account live, assign roles and make reconciliations simple for future audits.
This guide is written for founders, finance managers, directors and non-resident owners of a new company. It shows how these initial steps tie into resolutions, statutory books and share certificates to avoid delays when seeking finance.
Operational benefits are simple: faster payments, cleaner invoicing and smoother reconciliations that help your business scale with confidence.
Key Takeaways
- Understand the practical meaning of the full setup phrase and its role in early operations.
- Follow a clear, sequential flow that matches bank and regulator expectations.
- Complete account setup, signatories and capital deposit to go live swiftly.
- Keep records and resolutions ready to prevent avoidable delays with banking partners.
- Good initial controls make invoicing, reconciliations and audits much easier as the business grows.
Why your post-incorporation banking setup matters in Singapore
A well‑configured corporate account is the practical backbone of any new Singapore business operation.
Separating personal and company finances for clean records
Use a dedicated bank account to ring‑fence business transactions. This prevents commingling and creates credible financial evidence for audits and stakeholders.
Clean trails make bookkeeping and bank reconciliations faster. Month‑end close and supplier reconciliations are simpler from the very first transaction.
How banking readiness supports tax, compliance, and day-to-day operations
A ready account supports timely tax filings and submissions to ACRA and IRAS. Traceable payments and consistent documentation meet key compliance expectations under singapore regulations.
Clear signatory rules and board approvals ease reviews and due diligence. Operational tasks — payroll, supplier payments, cards and reimbursements — run with less friction.
“A structured account setup reduces risk and speeds growth.”
- Transparent records that auditors and lenders trust.
- Faster month‑end and simpler reconciliations.
- Lower governance risk during reviews of singapore companies.
- Scale confidently into multi‑currency and higher volumes.
Choose your Financial Year End to align banking and reporting cycles
The date you pick as your financial year end sets the rhythm for reporting, reconciliations and audits.
What an FYE is and why it matters: Your financial year end (FYE) marks the end of a reporting period. Choosing it early simplifies monthly closes, statement downloads and reconciliations. This makes treasury work and bookkeeping tasks more predictable and less error‑prone.
Common dates and how to decide
Many local firms use 31 March, 30 June, 30 September or 31 December. Pick a date that reflects seasonality and when revenue peaks or troughs. If your annual revenue is seasonal, align FYE to capture a complete trading cycle for clearer results.
How FYE drives statutory timelines
The chosen year end sets deadlines for Estimated Chargeable Income (ECI), the annual general meeting and annual returns. ECI is due within three months after FYE; the AGM must occur within six months; and filing annual returns is required within seven months.
- Consistent bank records reduce last‑minute reconstruction of transactions.
- Decide who owns the compliance calendar and which bank documents to retain for registration and filings.
- Ensure systems map monthly processes to the FYE to ease filing annual returns acra and returns acra obligations.
Prepare your corporate bank account pack before approaching a bank
Gather key documents in advance to reduce back‑and‑forth and shorten approval times.
Compile a single, secure document pack that you can share with prospective banks. This speeds verification and presents clear governance evidence.
Core incorporation documents
Include the Certificate of Incorporation and the company Constitution. Banks use these to verify legal existence and permitted activities.
Board authorisation
Provide a board resolution that authorises the account opening, named signatories, and operating mandates. Lenders treat this as essential governance proof.
Entity and ID verification
Attach the business profile and registration extracts to confirm directors and authorised persons.
Also include identity and address proof for directors, shareholders and ultimate beneficiaries. High‑risk profiles may trigger enhanced due diligence.
| Document | Purpose | Who provides | Notes |
|---|---|---|---|
| Certificate of Incorporation | Legal existence | Registered office | Certified copy recommended |
| Company Constitution | Permitted activities | Directors | Shows authorised signatures |
| Board resolution | Authorisation to open account | Board | Specify bank and signatories |
| ID & address proof | AML/KYC | Directors, shareholders, beneficiaries | Provide certified copies if requested |
Tip: Store files securely in a shareable format and keep certified copies ready. This helps you open corporate accounts more quickly and access relevant services when required.
banking checklist after company incorporation singapore
Turn the setup sequence into a clear workflow so you can open corporate bank relationships without delay.
Select the right corporate bank. Match your transaction profile to a provider: local FAST/GIRO volume, incoming international transfers, card processing and any cash handling needs. Compare account fees, monthly limits and digital banking features when deciding.
Confirm in‑person versus digital opening rules. Note that many banks will ask for physical presence of signatories or a majority of directors, while some digital banks allow remote onboarding for founders outside the jurisdiction.
Plan signatories and approval rules early. Define who signs, single versus dual authorisation and payment thresholds. Clear mandates reduce fraud risk and speed treasury operations.
Activate online and payment tools immediately. Enable online access, multi‑currency sub‑accounts if needed, payment whitelists and real‑time alerts. Set up user roles and limits to match governance.
Deposit share capital once the account is live. Instruct shareholders to transfer their subscribed capital and retain all bank receipts as evidence for statutory records and audits.
“A structured account setup turns initial paperwork into working operations quickly.”
Choose a bank account structure that fits operations and controls
Decide how your account structure will support daily operations and internal controls from day one.
Single versus dual authorisation for payments and transfers
Single‑authorisation suits lean start‑ups where speed matters and the number of signatories is small. It lets one authorised person approve routine payments quickly.
Dual‑authorisation gives stronger checks and works well for multi‑director governance. Require two approvers for large transfers to reduce fraud risk and meet stricter audit expectations.
Expense management, cards, and transaction limits
Set tiered approval rules: dual approval for transfers above a set threshold, single approval for low‑risk recurring payments, and role limits for junior staff.
Use corporate cards for routine purchases and a clear reimbursement flow for ad‑hoc spend. Align spend categories with your chart of accounts to keep reporting simple and accurate.
| Feature | Single Authorisation | Dual Authorisation |
|---|---|---|
| Best for | Small teams, fast payments | Multi‑director firms, higher value flows |
| Control example | Single signature for recurring payroll | Two approvals for transfers > S$10,000 |
| Fraud protection | Lower — rely on monitoring | Higher — requires independent sign‑off |
| Integration | Simple bank feeds to accounting | Role‑based permissions and audit trails |
Integrate your account with accounting software or outsourced services so bank feeds, receipts and approvals sync automatically. Named administrators, periodic access reviews and documented approval policies form the minimum controls hygiene banks and auditors expect.
Tip: Review authorisation rules as your business grows and consult the linked roundup of best business bank accounts when choosing providers that match your operational needs.
Appoint a corporate secretary to keep banking and corporate actions compliant
Securing a resident company secretary within the first months keeps statutory duties on track.
Legal deadline: Every new entity must appoint a company secretary within six months of incorporation to avoid breaching the Companies Act.
Eligibility in practice: The secretary must be a natural person residing in Singapore, cannot be the sole director, and should be professionally qualified or demonstrably experienced.
How secretarial support aids filings and governance
The secretary prepares board resolutions, maintains statutory registers and issues certified extracts that banks often require for account changes.
Common actions include adding or removing signatories, updating mandates, recording director and shareholder changes, and supplying certified documents for lenders or auditors.
Risk reduction: Ongoing secretarial oversight improves compliance and keeps records tidy as the singapore company begins to transact more heavily.
Practical rhythm
- Maintain a compliance calendar aligned to your FYE.
- Send directors reminders ahead of filing deadlines.
- Keep certified copies and minutes ready for quick verification.
“Clear secretarial processes speed bank onboarding and reduce delays.”
Set up statutory books and corporate records for smooth financial administration
A tidy set of corporate records speeds verification and reduces friction for major transactions.
What statutory books are: They are legal records kept at the registered office and must be current and available for inspection. Accurate entries help with routine checks and lender due diligence.
Registers to maintain
Keep up-to-date registers for directors, secretaries and shareholders, and a clear history of share transfers.
These registers support KYC requests and prove governance when banks or lenders review the entity.
Minutes and resolutions as evidence
Store minutes and signed resolutions that authorise account mandates, credit facilities and signatory changes.
Make an evidence folder so authorised bank actions can be verified quickly during approvals.
Charges, debentures and secured borrowing
Record any charges or debentures clearly. Lenders require transparent security records before granting facilities.
Update filings and the charges register promptly when security is created or released.
| Record | Why it matters | Who maintains |
|---|---|---|
| Directors register | Proves governance and authorised signatories | Company secretary |
| Shareholders & transfers | Shows ownership for capital and KYC | Company secretary |
| Minutes & resolutions | Evidence for mandates and financing | Company secretary |
| Charges / debentures | Records security for lenders | Company secretary & directors |
Responsibility: The company secretary usually maintains these records, but directors must review them periodically to ensure accuracy and compliance.
Issue share certificates and confirm shareholding details early
Issue formal share documents early to prove ownership and speed verification for third parties.
Why act now: Banks and regulators often ask for ownership evidence during onboarding and when checking beneficial owners. Promptly issuing share certificates avoids delays and supports clear governance.
Execution options: Certificates are usually issued under the common seal and signed by two directors or by one director and the secretary. Where no seal is used, authorised signatures are required — commonly two directors, one director plus the secretary, or one director with a witness.
Match every certificate to the register of members so shareholding details remain consistent across statutory books and investor documents. Mismatches create admin risk and slow approvals.
- Reissue is needed after transfers, splits, consolidations, reclassification or restructuring.
- Store certified copies, log certificate numbers, and attach board approvals when updating registers.
- Ensure share capital deposits align with issued certificates and register entries.
| Action | Why it matters | Who signs |
|---|---|---|
| Initial issue | Proves ownership for third-party checks | Two directors or director + secretary |
| Issue without seal | Permitted if authorised signatures/witness present | Two directors or director + secretary or director + witness |
| Reissue | After transfer, split, consolidation, reclass | As above; update register immediately |
“Timely, accurate certificates reduce downstream admin and support faster verification.”
Buy and control the company seal where required for official documents
A proper seal process reduces delays when original documents are needed for facilities or ownership proof.
A common seal is a metallic, ink‑free embossed device that shows the company name and registration number. It is used to produce a raised impression on share certificates and certain loan or facility documents when counterparties ask for sealed execution.
How the common seal is used on share certificates and loan documents
Sealed execution signals formality. Lenders or registrars sometimes require a sealed original for acceptance. Use it where legal or contractual practice demands a physical imprint.
Custody and countersigning practices led by the company secretary
Governance: A board resolution must authorise each use of the seal to create a clear audit trail.
- Typical countersigning: two directors, or one director and the company secretary.
- Custody: keep the seal under the control of the company secretary, log each use, and limit access to authorised staff.
- Controls: record the date, document type and signatories when the seal is affixed.
“A controlled seal process prevents last‑minute delays when banks request executed originals for mandates or facilities.”
Implement an accounting system that supports Singapore Financial Reporting Standards
From day one, record every transaction so your financial records stay audit-ready.
Tracking income and expenses from the first transaction
Set a baseline: maintain accounting books in line with SFRS and capture each sale, receipt and expense immediately.
Use disciplined invoicing, prompt receipt capture and clear categorisation rules. Reconcile monthly against bank statements to keep balances aligned.
Choosing software versus outsourcing accounting services
Small teams often save time with cloud software like Xero or QuickBooks. These platforms automate feeds and reduce manual entry.
Outsourcing to a firm can be more cost-effective when volume grows, or compliance needs become complex.
Maintaining records to support reconciliations and audits
Good records make preparing financial statements straightforward and reduce stress at FYE. Keep documents, receipts and signed approvals in one accessible folder.
“Clear trails and regular reconciliations prevent surprises during an audit.”
| Task | Practical step | Benefit |
|---|---|---|
| Daily capture | Record invoices and expenses within 48 hours | Accurate company financials |
| Monthly reconciliation | Match ledger to bank statements | Clean trial balance for reporting |
| System choice | Software or outsourced firm | Scales with team and audit needs |
Register for Goods and Services Tax when thresholds or strategy require it
Knowing when to register for GST helps prevent penalties and surprises.
Goods services tax is a value‑added charge on goods and services. It affects pricing, bookkeeping and cashflow. Clear bank records and sales ledgers are vital to prove taxable supplies and measure turnover.
When registration is mandatory
If your annual revenue exceeded S$1 million in the last 12 months, you must register for GST. Registration is also required if you reasonably expect turnover to exceed S$1 million in the next 12 months. Use deposits, sales ledgers and accounting reports to assess the trigger promptly.
Voluntary registration and operational changes
Smaller businesses may opt to register voluntarily if they serve GST‑registered clients or incur significant GST on purchases. Voluntary registration can allow input tax recovery but adds compliance duties.
- Charge GST on invoices, file returns and remit collected amounts on schedule.
- Keep separate tax set‑asides, use clear payment references and reconcile regularly.
“Good records and early assessment make GST manageable and prevent retroactive liabilities.”
Meet IRAS and ACRA filing obligations that depend on accurate bank records
Timely submissions to IRAS and ACRA rely on clear transaction trails and accurate records.
Filing Estimated Chargeable Income within three months
ECI represents your estimated taxable income after allowable deductions. Reconciled bank activity reduces errors in reported revenue and expenses, making ECI filings cleaner and quicker to prepare.
Holding the AGM and approving financial statements
The AGM must be held within six months of year end so shareholders can review and approve financial statements. Virtual meetings or document exchange are acceptable where permitted.
Filing annual returns with ACRA within seven months
A company must file annual returns within seven months of the financial year end. Some filings require XBRL financial statements; keep reconciled ledgers ready to avoid mismatches when filing annual returns acra.
Submitting corporate tax returns to IRAS
File Form C‑S or Form C depending on revenue and claim complexity. Consistent company financial records and tax computations speed online submissions and reduce queries.
Audit decision checkpoint
If revenue or total assets exceed S$10m, or employees exceed 50, appoint an auditor and tighten recordkeeping. Salary payments and statutory contributions must be traceable in payroll records to support tax positions.
“Good reconciliations turn regulatory work from a scramble into routine.”
Conclusion
A solid account and records routine turns early admin into a platform for growth.
Summary: Choose your FYE, prepare the full account pack, open the account, set clear authorisations and lock in disciplined recordkeeping and compliance routines.
Accurate governance reduces errors and speeds day‑to‑day operations. Keep key documents ready: board resolutions, statutory registers and issued share certificates. Where used, control the common seal and log every use to avoid delays when verifying mandates.
Remember the FYE milestones — ECI, the AGM, annual returns and corporate tax filings — and use regular reconciliations to lower regulatory risk and potential penalties under singapore regulations.
Next step: Turn this plan into a short timeline for the first weeks and assign responsibilities to directors, finance and secretarial services so the new business scales with confidence.
FAQ
What documents do I need to open a corporate bank account in Singapore?
When should I decide my financial year end (FYE)?
How does account signatory setup affect corporate controls?
Do I need to deposit share capital before opening the account?
What differences exist between in-person and digital account opening?
When must I appoint a company secretary?
Which registers and minutes should I keep for banking and compliance?
How do share certificates affect bank or financing transactions?
Is a company seal still necessary for banks and legal documents?
What accounting practices should I implement from the first transaction?
When must my company register for Goods and Services Tax (GST)?
FAQ
What documents do I need to open a corporate bank account in Singapore?
Most banks request the certificate of incorporation, the company constitution, a board resolution approving the account opening, and a business profile from ACRA. They also need identity and address proof for directors, shareholders and ultimate beneficial owners. Prepare certified or notarised copies if you plan to apply remotely.
When should I decide my financial year end (FYE)?
Choose an FYE that aligns with your trading cycles and simplifies reporting. Common dates include 31 December or 31 March, but you may select any date. The chosen FYE sets deadlines for estimated chargeable income (ECI), the annual general meeting (AGM) and filing annual returns with ACRA.
How does account signatory setup affect corporate controls?
Signatory rules determine who can approve payments and at what thresholds. Single authorisation speeds operations, while dual authorisation strengthens internal control. Match the arrangement to your governance, shareholder agreements and bank product capabilities.
Do I need to deposit share capital before opening the account?
You should be ready to deposit paid-up capital once the account is live. Some banks require proof of capital deposit for certain incorporation flows, so plan funds and supporting documentation in advance.
What differences exist between in-person and digital account opening?
In-person openings often allow faster identity verification and fewer certified documents. Digital onboarding can be convenient but may require video interviews, additional certifications and longer processing times depending on the bank and directors’ residency.
When must I appoint a company secretary?
Singapore law requires a company secretary to be appointed within six months of incorporation. The secretary must be ordinarily resident in Singapore and helps manage filings, minutes and bank resolutions.
Which registers and minutes should I keep for banking and compliance?
Maintain registers for directors, secretaries, shareholders and share transfers. Keep minutes of board meetings and resolutions authorising account openings, loans or charges. Accurate records support bank audits and statutory filings.
How do share certificates affect bank or financing transactions?
Share certificates confirm ownership and are often requested for due diligence. If shares move, reissue certificates promptly. Lenders may also require evidence of shareholding and corporate seals for security documents.
Is a company seal still necessary for banks and legal documents?
Many transactions proceed without a common seal, but some contracts, share certificates or mortgage deeds may still use it. The company secretary typically controls custody and countersigning, so retain or procure a seal if your advisers recommend it.
What accounting practices should I implement from the first transaction?
Start ledger entries, bank reconciliations and expense tracking immediately. Use accounting software aligned with Singapore Financial Reporting Standards or engage outsourced services. Well-maintained records simplify monthly reconciliations and annual audit or review requirements.
When must my company register for Goods and Services Tax (GST)?
GST registration becomes mandatory once taxable turnover exceeds S
FAQ
What documents do I need to open a corporate bank account in Singapore?
Most banks request the certificate of incorporation, the company constitution, a board resolution approving the account opening, and a business profile from ACRA. They also need identity and address proof for directors, shareholders and ultimate beneficial owners. Prepare certified or notarised copies if you plan to apply remotely.
When should I decide my financial year end (FYE)?
Choose an FYE that aligns with your trading cycles and simplifies reporting. Common dates include 31 December or 31 March, but you may select any date. The chosen FYE sets deadlines for estimated chargeable income (ECI), the annual general meeting (AGM) and filing annual returns with ACRA.
How does account signatory setup affect corporate controls?
Signatory rules determine who can approve payments and at what thresholds. Single authorisation speeds operations, while dual authorisation strengthens internal control. Match the arrangement to your governance, shareholder agreements and bank product capabilities.
Do I need to deposit share capital before opening the account?
You should be ready to deposit paid-up capital once the account is live. Some banks require proof of capital deposit for certain incorporation flows, so plan funds and supporting documentation in advance.
What differences exist between in-person and digital account opening?
In-person openings often allow faster identity verification and fewer certified documents. Digital onboarding can be convenient but may require video interviews, additional certifications and longer processing times depending on the bank and directors’ residency.
When must I appoint a company secretary?
Singapore law requires a company secretary to be appointed within six months of incorporation. The secretary must be ordinarily resident in Singapore and helps manage filings, minutes and bank resolutions.
Which registers and minutes should I keep for banking and compliance?
Maintain registers for directors, secretaries, shareholders and share transfers. Keep minutes of board meetings and resolutions authorising account openings, loans or charges. Accurate records support bank audits and statutory filings.
How do share certificates affect bank or financing transactions?
Share certificates confirm ownership and are often requested for due diligence. If shares move, reissue certificates promptly. Lenders may also require evidence of shareholding and corporate seals for security documents.
Is a company seal still necessary for banks and legal documents?
Many transactions proceed without a common seal, but some contracts, share certificates or mortgage deeds may still use it. The company secretary typically controls custody and countersigning, so retain or procure a seal if your advisers recommend it.
What accounting practices should I implement from the first transaction?
Start ledger entries, bank reconciliations and expense tracking immediately. Use accounting software aligned with Singapore Financial Reporting Standards or engage outsourced services. Well-maintained records simplify monthly reconciliations and annual audit or review requirements.
When must my company register for Goods and Services Tax (GST)?
GST registration becomes mandatory once taxable turnover exceeds S$1 million in a 12‑month period. You may opt for voluntary registration earlier for input tax recovery or commercial reasons; consult a tax adviser to assess the benefits.
What filing deadlines depend on accurate bank records?
Accurate bank statements underpin your ECI filing within three months of the FYE, the AGM held within six months of FYE, and ACRA annual return filing within seven months of FYE. Corporate tax returns (Form C or C-S) and any audit work also rely on robust financial records.
When must a company appoint an auditor?
Small companies that meet the audit exemption criteria may avoid appointing an auditor. If your company no longer qualifies—due to revenue, asset size or group structure—you must appoint an auditor and prepare financial statements in accordance with SFRS.
How can I choose the right bank account features for my business?
Evaluate multi-currency capabilities, online payment tools, transaction limits, corporate cards and APIs. Match features to your transaction volume, international exposure and treasury needs. Seek banks experienced in your industry for tailored services.
What supporting records do banks review for lending or charges?
Lenders request minutes, certified board resolutions, registers of charges and debenture documents. They will also review audited or management accounts, cashflow projections and credit histories. Keeping these records current expedites borrowing processes.
million in a 12‑month period. You may opt for voluntary registration earlier for input tax recovery or commercial reasons; consult a tax adviser to assess the benefits.
What filing deadlines depend on accurate bank records?
Accurate bank statements underpin your ECI filing within three months of the FYE, the AGM held within six months of FYE, and ACRA annual return filing within seven months of FYE. Corporate tax returns (Form C or C-S) and any audit work also rely on robust financial records.
When must a company appoint an auditor?
Small companies that meet the audit exemption criteria may avoid appointing an auditor. If your company no longer qualifies—due to revenue, asset size or group structure—you must appoint an auditor and prepare financial statements in accordance with SFRS.
How can I choose the right bank account features for my business?
Evaluate multi-currency capabilities, online payment tools, transaction limits, corporate cards and APIs. Match features to your transaction volume, international exposure and treasury needs. Seek banks experienced in your industry for tailored services.
What supporting records do banks review for lending or charges?
Lenders request minutes, certified board resolutions, registers of charges and debenture documents. They will also review audited or management accounts, cashflow projections and credit histories. Keeping these records current expedites borrowing processes.
What filing deadlines depend on accurate bank records?
When must a company appoint an auditor?
How can I choose the right bank account features for my business?
What supporting records do banks review for lending or charges?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.