Curious whether a Singapore-incorporated private limited company that earns most income abroad is the right move for your business? This guide cuts through the marketing and explains what buyers really mean when they search for a compliant approach to cross-border operations.
We define the term clearly, then set realistic expectations: this is a regulated, high-reputation jurisdiction focused on credibility rather than secrecy. You will learn practical checks before paying for incorporation, banking or ongoing compliance.
Expect a decision framework that covers fit (who it suits), tax mechanics, entity selection and the documentation you need. The guide uses current, real-world requirements — ACRA and IRAS filings, bank due diligence — so you can budget time and cost accurately.
Outcomes depend on facts such as income sourcing, remittance, substance and where management and control sits, not on bold marketing claims. Read on to see what to evaluate next.
Key Takeaways
- Definitions focus on function: a local-incorporated company operating mostly abroad.
- Credibility and predictable rules matter more than lowest tax rates.
- Assess fit, tax mechanics, entity choice and documentation before committing.
- Plan for ACRA/IRAS filings and thorough bank due diligence.
- Tax and compliance outcomes hinge on real facts, not promotional promises.
What a “Singapore offshore company” really means in practice
In many cases the phrase describes a standard private limited company used to serve foreign markets, not a unique legal form. There is no special offshore company law; the Companies Act governs the same entity type.
The operational meaning is simple: revenue, customers and day-to-day activities are mostly abroad. An offshore company will often have directors who make decisions outside the registry country and contracts with non‑resident clients.
Typical characteristics
- 100% foreign ownership is permitted.
- Can hold IP, contracts, brand and bank accounts for global business.
- Transparent, regulated company with required filings and KYC.
Common legitimate use cases
International trade: acts as the contracting party for cross-border sales.
IP and brand ownership: holds licences and manages royalty flows for investment in products.
Holding assets: used as a parent entity for subsidiaries and passive investments.
| Use case | Main role | Typical benefit |
|---|---|---|
| International trade | Contracting entity | Centralised invoicing and credit terms |
| IP ownership | Licence holder | Clear rights management |
| Investment holding | Parent company | Group governance and asset protection |
Choice of jurisdictions and where core functions sit affects tax, banking acceptance and compliance load. Not every business benefits—especially if income is domestic or lacks commercial rationale.
Who this option is for (and who should avoid it)
Deciding whether this model suits your enterprise starts with a clear view of where customers, decisions and cash sit.
Best fits are digital, e-commerce and tech businesses with globally distributed customers. These businesses use a local-incorporated company to contract, collect income and expand into new markets.
Typical buyer profiles include scalable digital services, cross-border trade platforms and companies seeking credible market access for growth.
Practical suitability checklist
- Customer mix: majority non-domestic clients.
- Work location: where services are delivered and by whom.
- Decision point: where senior management meets and decides.
- IP ownership: whether the entity holds licences or rights.
Key red flags
Avoid this route if your revenue is purely domestic, the commercial purpose is unclear, or control relies on nominee-only arrangements. Expecting secrecy or no reporting is unrealistic.
| Scenario | Likely outcome | Action |
|---|---|---|
| Mostly foreign customers | Commercially aligned; tax planning may work | Document contracts and decision-making |
| Domestic-only income | Limited benefit; higher compliance cost | Keep activity local; review options |
| Owners tax-resident elsewhere | Home-country tax may apply | Obtain residency and tax advice |
Singapore offshore structure pros and cons
Before committing funds, weigh what you gain against the operational commitments required to keep a local-incorporated company credible.
Credibility, access and markets
Benefit: A recognised company often reduces friction with partners, platforms and payment providers. This gives better access to international markets and reputable service providers.
Tax features that matter
Benefit: Tax rules include a headline corporate tax rate of around 17%, a territorial approach, no capital gains tax and no tax on dividends in many cases. Startup exemptions and partial relief can help early-stage businesses.
Legal stability
Benefit: English common law foundations and predictable contract enforcement support long-term planning and dispute resolution.
What you must commit to
Cost of credibility: Annual filings with the registry and tax authority, resident management roles and proper statutory records are mandatory. These compliance requirements are not optional.
Tax outcomes and banking reality
Tax benefits are fact-driven — sourcing, remittance and genuine substance decide the result.
Expect banks to request detailed documents and ongoing reviews; account approval is not guaranteed without clear commercial substance.
| Gain | Operational commitment | Practical note |
|---|---|---|
| Improved credibility | Governance and filings | Helps win partners, but costs time |
| Access to global markets | Management presence and records | Facilitates contracts and payment rails |
| Attractive tax features | Evidence of substance and sourcing | Outcomes depend on facts, not labels |
Tax considerations buyers must understand before they commit
Good tax planning starts with mapping where income arises and who will report it. This determines whether a local-incorporated company will be taxed on that revenue.
Corporate tax baseline and the territorial approach
Corporate tax is commonly quoted at around 17% as a headline rate. The important point is the territorial method: the system taxes income sourced in the country rather than taxing everything simply because a company is registered there.
Foreign-source income and when remittance matters
Foreign-source income is often outside local tax unless it is brought into the jurisdiction. Whether remittance matters depends on the type of income and specific rules that apply.
Buyers should map payment flows and keep contracts that show where services are performed. That evidence affects how income is characterised for tax purposes.
Dividend and capital gains treatment
Dividends are generally not taxed when paid, and there is commonly no capital gains tax. This can make a company attractive for holding assets and investment activity.
Startup exemptions and partial relief
Startup exemptions and partial relief exist for qualifying new businesses, but eligibility is not automatic. Criteria typically include levels of income, local management and genuine activity.
Finally, owners who remain tax-resident in another country may face home-country taxation or anti-deferral rules. Match expectations to reality by mapping fund flows, residency facts and reporting obligations before you commit.
Choosing the right Singapore entity and structure for your goal
Selecting an entity should put practical operations, liability and banking acceptance at the forefront. Match what you need—trading, holding, market entry or professional services—to the legal form that supports those aims.
Private limited company as the standard vehicle
A private limited company is the default for many buyers. It offers limited liability, a familiar company format and flexibility for contracts and ownership.
This entity can have up to 50 shareholders and acts as a separate legal person for most commercial activity.
Other options and when they fit
Exempt private company suits small holding or family businesses with no corporate shareholders and a 20-shareholder cap. It often means lighter compliance.
Branch gives a presence without a new legal person, but parent liability follows the branch. A representative office is limited to research and liaison; it cannot trade.
LLP or partnership fits professional groups where partners prefer personal responsibility for their own actions rather than corporate liability.
| Entity | Best for | Key limit |
|---|---|---|
| Private limited company | Trading, holding, group operations | Up to 50 shareholders |
| Exempt private company | Small groups, family holding | No corporate shareholders; max 20 |
| Branch / Representative office | Market entry, research | Branch: parent liability; Rep office: no revenue |
| LLP | Professional partnerships | Partners liable for own acts |
Practical note: entity choice influences bank risk assessments, annual filings and how the country or jurisdiction treats tax. Plan the incorporation with those factors in mind.
Incorporation requirements and setup documents you will need
Before any filing, clarify who will act locally, what records you will keep and which documents you must present.
Statutory roles and the registered address
A resident director, a local company secretary and a registered office address are non-negotiable requirements. The director must be present in the jurisdiction for regular decision-making. The secretary maintains statutory registers and files returns.
Share capital, shareholders and constitution essentials
Private companies need between 1 and 50 shareholders. Foreign ownership is allowed and paid-up capital can start from S$1. A standard constitution governs internal rules and share rights.
KYC and required documents
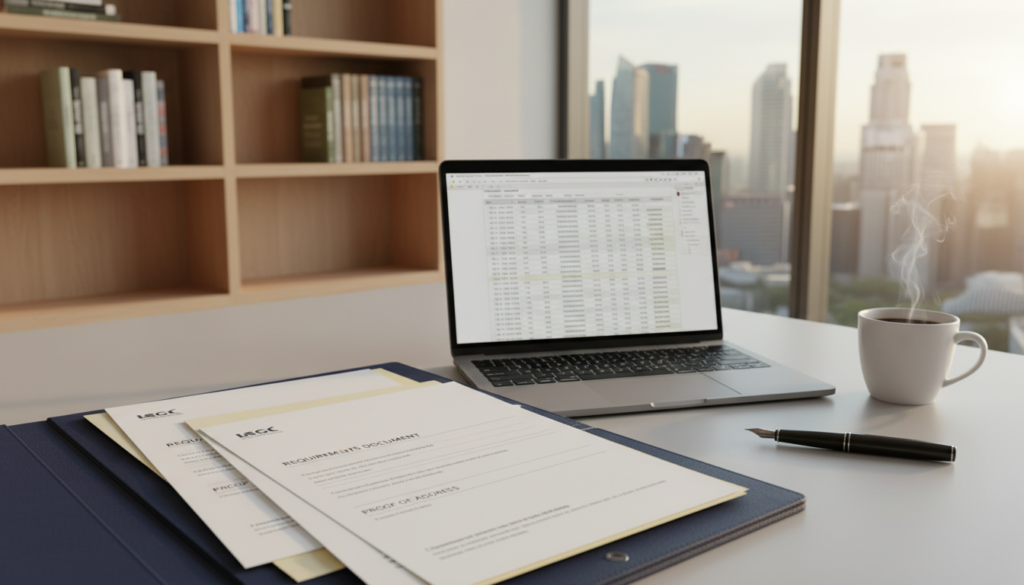
Prepare passports, proof of address, a clear business description and corporate documents where relevant. Clear documents reduce queries and speed approval.
Filing agents and nominee services
A registered filing agent submits incorporation to the registry and reduces rejection risk. Nominee services can meet local presence requirements, but must not replace genuine control.
- Checklist: passport, proof address, business plan, shareholder list, paid-up capital detail.
- Expect the same narrative for any company account opening later.
- Use reputable incorporation services like incorporation services and review provider terms and conditions.
| Item | What to prepare | Why it matters |
|---|---|---|
| Resident director | Local name and ID | Demonstrates decision-making presence |
| Registered address | Commercial or agent address | Statutory contact point for filings |
| KYC pack | Passport, proof address, business description | Needed for incorporation and account checks |
| Share details | Owners list, paid-up capital | Sets ownership and capital structure |
How to set up a Singapore offshore company: end-to-end process
Start with tax residency and commercial fit before any filing: assess your home‑country tax rules and where owners are tax‑resident. Only after this design the operating model and decide which assets the company will own.
Pre-setup planning: define ownership and functions
Decide whether the company will hold IP, contracts or handle receipts for cross‑border trade. Document each function and the staff or agents that will carry it out.
Name reservation and incorporation timeline
Name reservation and registry filing are quick if documents are ready. Expect incorporation to take 1–7 business days once KYC and director details are complete.
Bank account or multi-currency fintech account
Compare a traditional bank account with a multi‑currency fintech option. Banks may require director attendance for due diligence; fintech accounts often open faster for payments and conversions.
Implementation: contracts, IP and invoicing
Novate contracts, set licensing or intercompany service agreements and update invoicing flows. Prepare transfer pricing notes to show commercial rationale.
Operational readiness: bookkeeping and management records
Set bookkeeping, schedule regular board meetings and keep written minutes. Strong documents and a clear management trail reduce friction in later bank reviews and tax audits.
- Step 1: Tax/residency analysis
- Step 2: Design who owns assets and conducts operations
- Step 3: Incorporate, open account, implement contracts, go live
| Phase | Typical timing | Key dependency |
|---|---|---|
| Name reservation + filing | 1–7 business days | KYC documents ready |
| Bank or fintech account | Days to weeks | Director due diligence |
| Implementation tasks | 1–6 weeks | Contract novations and IP transfers |
Compliance and reporting: what you must file each year
Annual filing is where the real cost and discipline of a compliant company becomes visible. Budgeting for these recurring duties helps buyers see beyond one-off incorporation fees and plan for ongoing obligations that affect banks, investors and directors.
ACRA annual return and statutory registers
The Annual Return with the registry must be filed on time. Maintain statutory registers, director and shareholder records, and a secure minute book. Appoint a company secretary within six months and keep registers current to satisfy governance requirements.
IRAS corporate income tax return and financial statements
Submit an annual corporate tax return with supporting financial statements. Good bookkeeping makes tax reporting accurate and reduces queries. Poor records lead to adjustments and extra charges.
Audit thresholds and triggers
An auditor must be appointed within three months unless the company meets exemption criteria. Audit requirements kick in as turnover and balance sheet tests are exceeded; check exemptions as you scale.
“Timely compliance is a commercial advantage: it reduces perceived risk for banks and strengthens legal defensibility.”
- Practical tip: create a compliance calendar and map responsibilities to director, secretary and accountant.
- Late filings and weak documents can trigger banking reviews and harm service relationships.
Banking, payments, and transactions: what to expect from banks
Opening a bank account for a locally incorporated company often requires more documentary proof than many buyers expect. Financial institutions in the region are cautious and apply strict anti-money‑laundering checks.
Common due diligence and meeting requirements
Banks will verify beneficial ownership, source of funds and the business model. Expect requests for director interviews; sometimes an in‑person meeting is required.
Documents that reduce friction
Prepare clear incorporation papers, shareholder and director IDs, proof of address and a concise business description.
Also include contracts, invoices, website pages and a short transaction narrative to show genuine operations.
Managing cross-border transactions and payment processors
Consistent invoicing and transparent counterparty details reduce flags on international transactions. Payment processors and fintech services can speed flows, but banks still review major rails for risk.
- Account opening pack: incorporation documents, KYC, proof address, contracts, sample invoices, website evidence.
- Ongoing reviews: periodic updates to the account, queries on transactions and requests for refreshed documents.
- Practical tip: strong governance and neat records make banking services smoother and cut the risk of account interruptions.
| Area | Typical bank check | What to prepare |
|---|---|---|
| Ownership | Beneficial owner verification | Shareholder register, IDs |
| Funds | Source-of-funds/wealth | Contracts, invoices, bank statements |
| Activity | Business model review | Website, marketing, transaction samples |
“Plan for diligence rather than assume instant approval.”
Substance, management, and control: protecting the structure’s integrity
Clear, documented decision-making by local officers gives a company the legitimacy it needs for banking, contracts and tax treatment.
What “real” local decision-making looks like for the resident director
Real management means the resident director takes part in board deliberations, approves major contracts and signs key corporate resolutions.
Expect the director to attend regular meetings, review budgets and authorise strategic hires or expenditures. This is not a passive role.
Evidence you should keep: minutes, resolutions, and operational documentation
Keep concise records that show who decided what, when and why. These items support credibility with banks and regulators.
- Board minutes and written resolutions
- Management accounts and signed agreements
- Operational logs, staff lists and activity reports
Economic substance expectations and global reporting standards
Economic substance is practical: people, premises and proportionate activities that match the company’s commercial role.
Global reporting and transparency rules make paper-only setups fragile. Poor substance can produce unexpected tax challenges and higher compliance costs.
“Good substance is the integrity layer that protects the company from challenge and supports long-term stability.”
Practical tip: align residency, management and operations with the company’s declared purpose to retain protection and avoid governance or tax surprises.
Choosing a provider: how to assess agents and corporate services
A capable provider reduces risk: they file accurately, explain annual duties and help you present a coherent story to banks when opening an account.
What to look for in incorporation, secretarial and compliance services
Choose services that show competence, transparency and a track record with similar businesses. Prefer firms that act as your filing agent and maintain statutory registers.
- Clear timelines: accurate filings and proactive reminders for deadlines.
- Document care: maintenance of minutes, resolutions and shareholder records.
- Banking support: help with narratives and account packs that reduce review friction.
Questions to ask about nominee arrangements, liability and governance
Ask what authority a nominee has, whether they sign documents, and how liability is allocated.
Request escalation paths for urgent approvals and clarity on how “real involvement” is evidenced.
Ongoing costs, renewal fees and service scope clarity
Obtain a written scope of work with itemised costs: incorporation, annual renewals, registered address, director services and ad‑hoc resolutions.
| Service | Typical fee | What to verify |
|---|---|---|
| Incorporation | One‑off fee | Filing timeline, KYC checklist |
| Registered address & secretary | Annual fee | Physical address, minute book access |
| Nominee director | Monthly / annual | Scope of authority, liability cover |
| Banking support | Flat or hourly | Account pack prep, meeting support |
Practical note: provider quality affects bank outcomes and long‑term protection of the company. Treat the choice as a jurisdiction strategy decision, not a price tender.
Conclusion
, A careful buyer treats incorporation as the start of a disciplined operational plan, not a quick fix.
A local-registered company can give firms credibility with partners and better access to global markets. Many companies use this route for cross-border trade and to hold assets or IP.
The realistic benefits include improved market access, territorial tax features and often no capital gains or dividend tax. These benefits only follow when governance, documentation and substance are in place.
Decide with facts: map customer geography, planned trade flows, asset ownership, investment goals and cash routes. Then build a one-page company map (entities, contracts, money flow, banking needs) and brief a qualified corporate services provider and tax adviser.
Done properly, this approach supports growth while preserving legitimacy and long-term commercial value.
FAQ
What does a Singapore offshore company really mean in practice?
Why is there no special offshore company law in Singapore?
What are typical characteristics of a Singapore-incorporated structure used for international activities?
What legitimate use cases suit this kind of company?
Which business models benefit most from foreign-source income?
What red flags indicate this setup might be unsuitable?
What are the main advantages of using a Singapore-incorporated vehicle for international business?
What are the key drawbacks to be aware of?
How does the corporate tax regime and territorial principle affect non-local income?
How are dividends and capital gains treated?
What entity types are commonly chosen for these purposes?
What are the core incorporation requirements and documents needed?
Can service providers offer nominee arrangements and what should I check?
What is the typical end-to-end setup process?
How long does incorporation and bank onboarding usually take?
What annual compliance filings are mandatory?
When is an audit required?
What do banks typically request during account opening and reviews?
How should cross-border transaction flows be managed?
What does genuine local management and control look like?
What records should be kept to prove substance and governance?
How do global economic substance expectations affect these companies?
How do I choose a corporate service provider?
What ongoing costs should I budget for?
Are there common compliance pitfalls to avoid?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.