Can a neutral third party really remove the biggest risk from high-value deals? This guide explains how an impartial agent can hold money and documents until agreed conditions are met, helping to prevent fraud and cut disputes.
Organisations in Singapore often need a trusted, neutral holding arrangement as part of their commercial and banking setups. A properly governed account ensures funds are only released when both sides meet clear criteria, improving trust and reducing counterparty risk.
This page is a practical, service-led guide. You will learn what an escrow account does, when it is used, and how a bank-grade approach to controls supports higher-value transactions.
It is aimed at corporates, investors, SMEs managing large purchases, project owners and disputing counterparties who need clearer requirements and reduced operational friction. For a worked example of an integrated approach, see Proxtera’s escrow process.
Key Takeaways
- An impartial account holder safeguards funds until conditions are met.
- Clear terms and bank-grade controls boost confidence in transactions.
- Common users include corporates, SMEs, investors and project owners.
- Expect protections for assets, a defined end-to-end process and dispute mitigation.
- The right provider reduces operational friction without promising legal outcomes.
How escrow services support secure business transactions in Singapore
When large sums or valuable assets change hands, a controlled holding arrangement reduces the risk of non-performance.
What an escrow service is and why an impartial escrow agent matters
An escrow service is an arrangement where an impartial third party holds funds or assets until agreed requirements are met.
Impartiality matters because cross-border deals or new counterparties raise trust and compliance concerns. A neutral agent removes pressure on one side to act first.
How escrow accounts protect funds, assets and payments until conditions are met
An account rings-fences assets through controlled access, documented release triggers and clear milestones.
Protection mechanics include staged releases, partial disbursements and holdbacks. These methods support contractual performance and reduce payment disputes.
Common scenarios: property, large deals and dispute-led holding
- Property conveyancing often uses a holding account managed by lawyers.
- Large commercial transactions—such as shipments or sizable invoices—use temporary custody to secure payments.
- Dispute-led holding parks funds pending remedial action or settlement, avoiding rushed payments.
“A neutral custodian lets both parties proceed with confidence while contractual conditions are verified.”
| Use case | Typical mechanism | Main benefit |
|---|---|---|
| Property sale | Lawyer-managed account; release on completion | Safe transfer of purchase funds and title |
| Large commercial deal | Staged release tied to delivery milestones | Aligns payment with performance |
| Dispute holding | Temporary park until remedial actions agreed | Reduces friction and litigation risk |
Next: Modern account arrangements can be tailored for complex, multi-party transactions that need robust reporting and governance.
Escrow services singapore business banking solutions for your transaction needs
Complex transactions now demand structured custody so parties can focus on deal delivery, not payment risk.
Safeguarding assets and reducing counterparty risk in complex transactions
Structured holding and staged release are core risk controls. A tailored account and bank-grade governance keep funds tied to clear triggers. This reduces premature payments and enforces contractual discipline.
Use cases: M&A, project finance, sustainable financing and litigation
- M&A: consideration holdbacks and escrowed warranties.
- Project finance: waterfall payments and completion-linked drawdowns.
- Sustainable financing: aligning proceeds with ESG outcomes (see July 2025 Sustainable Cash Escrow and Account Bank concept).
- Royalties, sales receipts and litigation holds pending settlement.
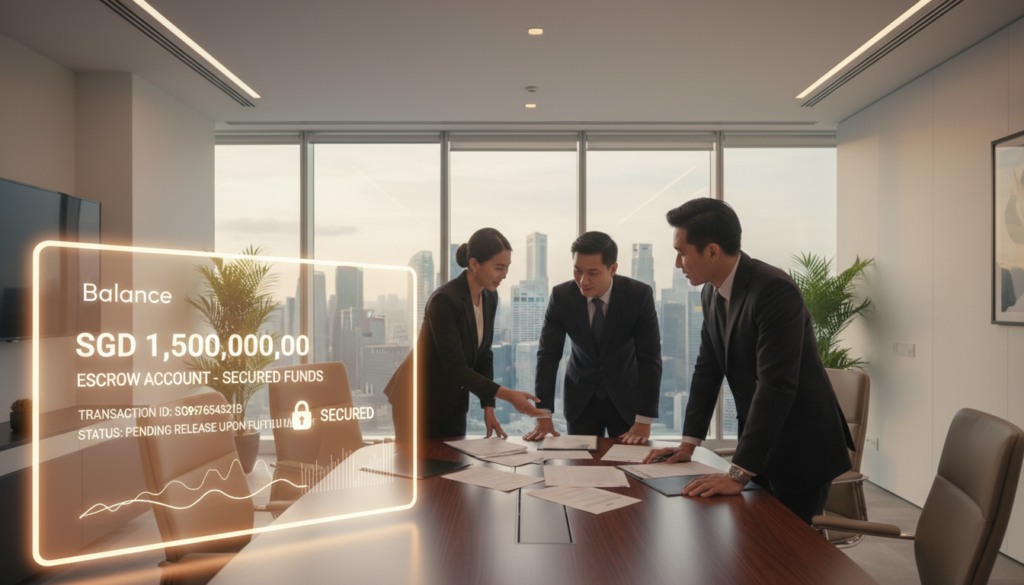
Holding and releasing funds at the right time
Funds are retained until drawdown dates, completion certificates or lender consents are confirmed. This supports disciplined cash management and reduces operational disputes.
Cross-border practicality and operational support
Local regulatory nuance affects exchange timing and documentation. Expect dedicated teams with deep experience to coordinate multi-jurisdiction releases and keep day-to-day admin efficient.
“Dedicated operational support and bank-grade governance make multi‑party releases predictable and auditable.”
| Use case | Typical arrangement | Primary benefit |
|---|---|---|
| M&A holdbacks | Time-limited account with staged release | Protects against post-closing claims |
| Project finance | Waterfall account; milestone-triggered disbursements | Aligns cashflow with delivery |
| Sustainable proceeds | Proceeds ring-fenced with ESG reporting | Combines risk control and sustainability outcomes |
How the escrow process works from deposit to disbursement
A structured chain of checks and approvals prevents last‑minute disputes in complex deals. The process moves through four clear stages so procurement, finance and legal teams can align responsibilities and timelines.
Escrow agreement: setting clear transaction requirements and release conditions
The agreement is the foundation. It defines documents, milestones and acceptance criteria. It also states who may instruct the custodian and what evidence is needed for release.
Deposit into the escrow account: secure cash holding and controlled access
Parties place funds or assets into the designated account under agreed terms. Segregation, controlled access and audit trails ensure the holding is secure and traceable.
Verification: confirming delivery, inspections and contractual milestones
Verification can include delivery receipts, inspection reports and completion certificates. If conditions are partially met, staged releases or holdbacks apply until disputes are resolved.
Release and exchange: disbursing funds and transferring ownership with confidence
Once evidence meets the requirements, the custodian disburses payments and triggers transfer of title or documents. Internal approvals, such as board resolutions, may be required for high‑value accounts.
“A predictable release process reduces friction and preserves trust between parties.”
- Agreement: define triggers, evidence and instruction rights.
- Deposit: secure holding, segregation and audit trail.
- Verify: inspections, receipts and milestone checks.
- Release: payments, title transfer and final accounting.
Choosing an escrow service provider in Singapore: what to check before you open an account
Choosing who will hold your transaction funds should be based on capability, not marketing claims. Use a short checklist to match a service provider to your deal size, risk profile and timeline.
Provider options and when to pick them
Compare banks for tight banking integration and cash management, law firms for conveyancing workflows, and the Singapore Academy of Law for institutional legal oversight.
Operational support
Dedicated teams and a single point of contact cut coordination time. Ask about handover plans, continuity and the team’s practical experience with similar transactions.
Visibility, governance and costs
Demand clear reporting, both online and offline, and the ability to change cash flows if contract terms shift.
Confirm documentation needs: the account terms, instruction mechanics in the escrow agreement and any required board resolutions for account opening or release.
| Provider type | Strength | When to choose | Typical fee reference |
|---|---|---|---|
| Bank | Cash management, online reporting | Complex multi‑party cashflows | Varies by deal; quoted per transaction |
| Law firm | Legal-led workflows, property conveyancing | Private property or litigation holds | S$2,500–S$5,000 (conveyancing benchmark) |
| Singapore Academy of Law | Institutional legal expertise | High‑risk legal settlements | Case dependent; request a quote |
“Match the provider’s capabilities to your transaction needs to gain clarity, reduce disputes and secure better outcomes.”
Checklist: suitability for risk, clear timelines, documentation complexity, operational support, reporting and transparent fees. The right provider delivers practical support and tangible benefits for both buyer and seller.
Conclusion
A controlled account removes uncertainty by tying release to objective evidence.
When conditions in the agreement are met, funds and assets are released. This protects both sides and reduces fraud and disputes.
How it works: agree terms, deposit funds, verify milestones, then release. The pathway is simple to implement and easy to audit.
Assess your needs—deal size, parties, cross‑border complexity and reporting—and choose a provider with the right operating model and controls.
For a concise primer on how a holding arrangement functions, see what an escrow is. Contact a specialist to structure an account that matches your timelines and documentation so all parties can proceed with confidence.
FAQ
What is an escrow service and why does an impartial agent matter?
How do escrow accounts protect funds, assets and payments until conditions are met?
In what scenarios are these arrangements commonly used in Singapore?
How can an arrangement reduce counterparty risk in complex transactions?
What are common business use cases such as M&A, project finance and royalties?
How are project and lending funds held and released at the right time?
How do these services support cross-border transactions with local regulatory nuance?
What should an escrow agreement include to set clear transaction requirements?
What happens during deposit into the escrow account?
How does verification of delivery, inspection and milestones work?
How are funds released and ownership exchanged with confidence?
What provider options exist: banks, law firms and the Singapore Academy of Law?
What operational support should I expect from a provider?
How do visibility and flexibility affect reporting and cash-flow adaptation?
What governance and documentation will be required before opening an account?
How do fees vary by transaction type and provider?
How do these arrangements provide confidence and support for payments and exchanges?
What experience should I look for in a provider handling high-value transactions?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.