How can a single payment instrument remove doubt, speed customs clearance and keep your shipments moving?
Importers, exporters and intermediaries in Singapore rely on a trade tool that assures sellers they will be paid when documents meet agreed terms. Major banks such as DBS even highlight strong credit ratings like “AA-” and “Aa1” to reassure suppliers that payment is bank-backed and secure.
Typical services include issuance, amendments, advising support, document checking and settlement. Many lenders now offer digital application and management — for example, apply online via DBS IDEAL — which shortens turnaround time for repeat transactions with regular suppliers.
The processing journey is straightforward: application → issuance → advising → presentation → examination → settlement. Fees differ by bank and facility; this page outlines common fee categories and planning points rather than a single tariff.
If you need assurance over shipping documents, payment protection or help structuring a guarantee for multi-party supply chains, this guide will help you choose the right structure and understand the features and timeframes that matter.
Key Takeaways
- Bank-backed instruments reduce cross-border payment risk and improve cash flow.
- Core services: issuance, amendments, advising, document checking and settlement.
- Digital platforms like DBS IDEAL speed up applications and repeat transactions.
- Issuing bank credit ratings help reassure suppliers about payment capability.
- Fees vary by provider; plan around common fee categories rather than a single price.
Why a Letter of Credit supports secure international trade payments
When banks guarantee payment against correct paperwork, suppliers trade with far less risk. The issuing bank undertakes to pay once a seller presents compliant documents. This reduces counterparty exposure and gives the buyer structured control over when funds are released.
Payment assurance and reduced counterparty risk
Suppliers gain confidence that they will receive payment for shipped goods when conditions are met. Buyers get reassurance that funds move only after transport and shipment conditions are proven by paperwork.
Document checking for compliant shipment
Banks examine transport documents and terms to spot errors before payment. That scrutiny cuts disputes, reduces costly amendments and speeds the presentation process.
Stronger trading relationships and new opportunities
A bank-backed mechanism helps firms safely trade with new suppliers and win better commercial terms. It can open markets and foster longer-term partnerships.
Cash flow advantages through trade finance terms
Structures such as deferred payment dates align cash collection with sales cycles and improve working capital. Trade teams at banks offer expertise to tailor conditions — shipment windows, partial shipments and presentation periods — so financing matches operational needs.
For a practical guide to export arrangements and benefits, see export letters.
letter of credit singapore business banking options for importers and exporters
Picking the right LC structure can reduce delays and free working capital for both buyer and seller. Below is a decision-focused summary that maps each common instrument to typical trade scenarios and funding needs.
Sight – payment on compliant presentation
Best when suppliers demand quick settlement. The issuing bank pays once documents meet terms. This keeps control tied to paperwork and speeds receipt for sellers.
Usance – deferred payment
Useful where buyers need extra days to manage cash flow. The bank accepts a draft and pays on the due date, giving sellers bank-backed certainty and buyers breathing room.
Red clause – partial advance
Enables an advance to fund production or shipment. It helps sellers with upfront costs but requires tight conditions to limit exposure for the buyer bank.
Transferable & Back-to-Back
Transferable supports intermediaries who must pass benefits to an ultimate seller without revealing the end buyer.
Back-to-back lets a master export instrument back a separate import facility so trading firms can finance procurement against sales.
| Type | When to use | Primary benefit | Key caution |
|---|---|---|---|
| Sight | Fast settlement required | Immediate payment on compliance | Requires flawless documents |
| Usance | Buyer needs credit days | Improves buyer cash flow | Seller waits for funds |
| Red Clause | Seller needs working capital | Partial advance funds production | Higher risk for payer bank |
| Transferable / Back-to-Back | Intermediary or financing trade | Enables multi-party fulfilment | Complex wording; watch discrepancies |
How Letter of Credit processing works in practice
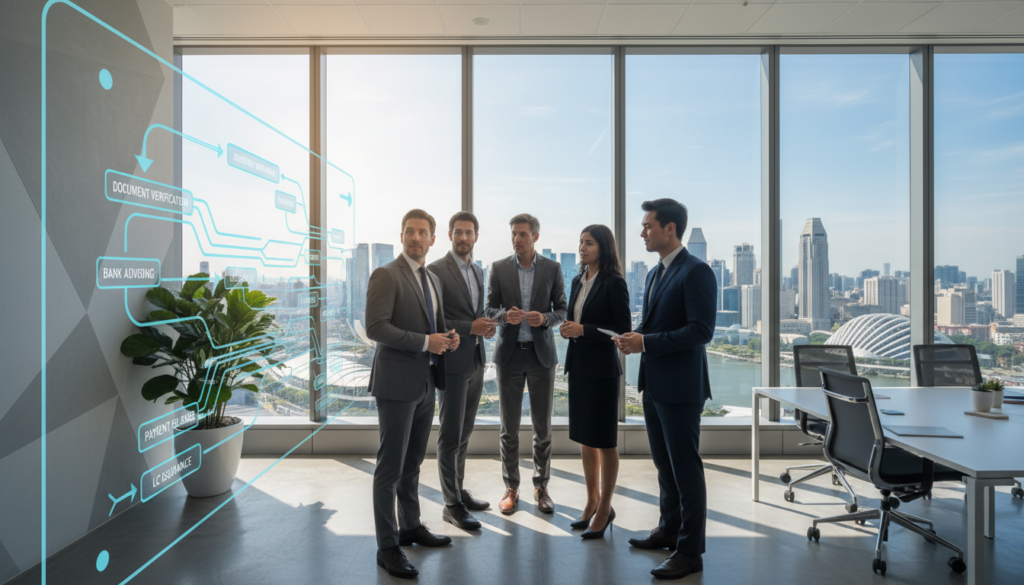
Understanding the step-by-step movement of documents and funds helps teams avoid delays at origin and destination.
Pre-shipment and submitting the request
Agree contract terms carefully. Match Incoterms, shipment dates and the exact documents required. Then the buyer submits an LC request to the issuing bank with the agreed wording and amount.
Advising and presenting banks
The issuing bank sends the instrument to a correspondent or advising bank in the seller’s country. That bank confirms authenticity and tells the seller how to present documents.
The seller delivers the set to a presenting bank, which forwards them to the issuing bank for examination and payment.
Post-shipment checks and release
Issuing banks examine documents for compliance. If compliant, payment follows and documents are released for customs clearance. For deferred drafts, acceptance triggers the payment schedule.
Common discrepancies include mismatched names, dates or invoice totals. Proactive checking reduces delays and amendment costs.
| Stage | Who acts | Key action | Timing |
|---|---|---|---|
| Pre-shipment | Buyer & seller | Agree contract, submit request | Before shipment |
| Advising | Issuing & advising bank | Notify seller, confirm terms | Hours–days |
| Presentation | Seller & presenting bank | Send documents to issuing bank | Within presentation window |
| Examination & release | Issuing bank & buyer | Pay or accept; release documents | Days, depending on discrepancies |
Applying online, required documents, and common fees in Singapore trade finance
Digital platforms let trade teams submit requests, attach supporting paperwork and monitor status in real time.
Digital application and management via business banking platforms
DBS IDEAL and OCBC Velocity let firms lodge an application, reuse templates for repeat suppliers and track multiple transactions on one screen.
Upload supporting documents online and retrieve electronic advices to reduce paper handling and speed processing. Real‑time status updates help teams plan customs clearance and collections.
What documents are typically checked and why accuracy matters
Issuing banks verify the commercial invoice, bill of lading or air waybill, packing list and any certificate of origin or inspection.
Insurance papers and payment drafts for usance must match the stated amount and conditions. Even small discrepancies can delay payment, incur amendment fees or require a buyer waiver.
Fees and charges to plan for
Budget for issuance fees, amendments (including increases and expiry extensions), acceptance charges for deferred drafts and cancellation fees.
For example, OCBC publishes an illustrative issuance charge of 0.125% monthly with minimum fee periods and thresholds (for instance higher minimums without an approved facility and lower minimums with one). Fixed charges for amendments (around S$60) and cancellations (around S$50) are common, though rates vary by provider and facility.
Using facilities, margins and limits
Having a trade facility usually lowers minimum fees and reduces margin requirements. Limits and collateral affect pricing and speed of approval.
Choose sight for quick cash release to suppliers, or usance when you need extra days to manage working capital. Align the issued amount and presentation windows with your procurement and sales cycles to avoid unexpected financing use or shortfalls.
| Area | What to check | Typical impact |
|---|---|---|
| Application channel | Portal templates, status tracking | Faster processing; audit trail |
| Documents | Invoice, transport docs, certificates | Payment timing; customs clearance |
| Fees | Issuance, amendments, acceptance | Budget forecasts; negotiation point |
Conclusion
For cross‑border deals, a documentary facility gives parties confidence and ties payment to verifiable shipment evidence.
Core value: a bank‑backed instrument reduces payment risk and keeps control linked to documentary compliance. Choose the right type — sight, usance, red clause, transferable or back‑to‑back — to match contract terms, supply chain shape and cash flow needs.
Execution depends on clear contract drafting, realistic document lists and early alignment with suppliers. Proactive discrepancy handling speeds release and lowers amendment costs.
Modern digital channels provide faster applications and real‑time tracking. Speak to a trade finance team to structure terms, review facility options and plan fees for your export and import profile.
FAQ
What is a Letter of Credit and how does it support secure international trade payments?
How does document checking work and why is accuracy important?
What types of facilities are available for importers and exporters?
How does a Sight Letter of Credit differ from a Usance Letter of Credit?
When would a Red Clause or Transferable LC be used?
What is a Back-to-Back structure and when is it appropriate?
What steps are involved in LC processing from pre-shipment to post-shipment?
How do advising and presenting banks differ in the process?
Can LC transactions be managed online and what platforms are used?
What documents do banks typically require when applying for an LC?
What fees and charges should companies expect with LC services?
How can businesses use facilities, margins and limits to align LC issuance with financing needs?
What assurances do banks offer to exporters and suppliers under LC arrangements?
How do amendments, discrepancies and cancellations affect LC transactions?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.