
How likely is your company to open a usable corporate bank account quickly, and what can you control to make that happen?
The practical meaning of “approval rate” here is simple: the likelihood your application is accepted without repeated queries and the chance the account is activated with needed features fast.
This guide accepts that providers rarely publish official percentages. Instead, it shows the controllable inputs—eligibility checks, correct documents, consistency of information and choosing the right provider—that raise your odds.
Think of this as a buyer’s guide: it helps you choose between a traditional bank and a fintech solution based on entity profile, cash position and transaction plan.
We preview the decision criteria you should compare: minimum initial deposit, average daily balance, ongoing fees, transaction pricing, online tools and multi-currency functionality.
Remember: being “approved” does not always mean “ready today.” Verification and activation steps, especially with remote onboarding, affect time-to-use. The article includes side-by-side comparisons of OCBC, UOB, CIMB and non-bank providers such as Airwallex, Aspire and Wise for clearer choices.
The intended audience is incorporated startups and SMEs, including founders applying remotely, who want fewer surprises and a smoother path to a usable banking setup.
Key Takeaways
- Approval likelihood depends on documentation, eligibility and provider fit.
- Official percentages are rare; focus on what you can control.
- Compare deposits, daily balance, fees, online tools and multi-currency options.
- Approval ≠ immediate usability; remote onboarding can add steps.
- Traditional banks and fintechs suit different profiles—choose by cash flow and transaction needs.
- This guide reviews OCBC, UOB, CIMB and non-bank alternatives to aid comparison.
What the business bank “approval rate” means and why it varies
Approval figures are shorthand for two different things: the chance your application passes initial checks, and the time until you can use core services.
Banks and fintechs run different risk checks and score legitimacy differently. Traditional banks often take a conservative view on complex ownership, higher-risk sectors and cross-border flows, especially when broader banking services are involved.
Fintechs can be faster for straightforward cases. Yet they will pause or reject applications if KYC evidence is incomplete or transaction plans look inconsistent with the stated model.
From submission to usable service
- Application received
- Identity verification
- Business verification and compliance review
- Account opened and features enabled (transfers, cards, user access)
Even after an account is created, token setup, limits or extra checks can delay full use. Your choice of provider also signals intent: a local SGD operating facility differs from a multi-currency, cross-border payments platform.
Most delays are preventable: inconsistent information, missing documents and unclear ownership or transaction purpose cause the bulk of friction. For details on credit-related readiness, see business loan requirements.
Why Singapore corporate bank account applications get rejected or delayed
When onboarding stalls, it is rarely random. Most delays happen because reviewers cannot reconcile ownership, operations or paperwork with the risk profile shown in forms and public records.
Common red flags
Opaque ownership chains and nominee-heavy structures trigger extra scrutiny. Reviewers want to know who ultimately controls funds and why.
Unclear models that fail to state who pays you, from where, and for what services raise suspicion. That can lead to rejection or long clarifications.
KYC friction points
Directors and shareholders each need ID and may face liveness/selfie checks. Inconsistent names, addresses or roles between ACRA, invoices and web pages slows review.
“Inconsistent information across documents is the single biggest cause of repeated compliance queries.”
Operational constraints
Some providers limit remote verification if signatories are overseas or documents are not locally verifiable. Others still require a branch visit for wet signatures or board resolutions.
- Typical triggers: opaque ownership, missing transaction purpose, nominee use without explanation.
- How to avoid delays: align forms, public records and invoices; state expected counterparties and monthly volumes clearly.
- Remember: fees and product rules matter. Failure to meet minimum balances can strain the relationship early and risk closure.
| Issue | Why it slows onboarding | Fix | Impact on time |
|---|---|---|---|
| Opaque ownership | Requires enhanced due diligence | Provide ultimate beneficial owner declaration | +7–14 days |
| Inconsistent documents | Triggers queries and follow-ups | Align ACRA, website and invoices | +3–10 days |
| Remote signatories | Limits online verification options | Arrange embassy/legalised docs or branch visit | +5–21 days |
| Low balance / fee issues | Raises closure risk | Choose products matching expected volumes | Ongoing |
Eligibility basics before you apply for a corporate bank account
Start by confirming a short checklist; eligibility is the gatekeeper to any formal review.
Entity type and registration. Your company must be legally registered in Singapore and the details you provide should match official records precisely. Use the registered address, director and shareholder names, and appointment dates that appear on public filings.
Residency and signatory rules. Providers set different rules for remote onboarding. Some allow full online setup for founders overseas. Others require at least one local director or a branch visit.
People matter as much as the company
Directors and significant shareholders face individual screening. Their identities, addresses and past roles can affect the outcome.
Nominee arrangements or unclear ownership often trigger extended checks. Be ready to explain who ultimately controls funds and why.
Start‑up age and starter bundles
Many providers offer starter packages for companies incorporated under three months or three years. These bundles can waive fees or lower balance requirements while the company is young.
Use “business age” as a filter when shortlisting providers: pick products designed for startups or new companies if that matches your profile.
- Confirm baseline items: legal registration and matching opening details.
- Check residency rules: remote onboarding vs local director needs.
- Remember people screening: directors and shareholders are assessed individually.
- Shortlist 2–3 providers that fit your profile before applying.
“Meeting eligibility allows review but does not guarantee a successful outcome; KYC and plausibility checks still apply.”
Documents checklist to improve approval odds
A clear, well-organised document pack shortens checks and cuts follow-up queries. Gather files so reviewers can verify identity, ownership and purpose quickly.
Proof of identity, address and selfie checks
Prepare certified IDs for directors and authorised signatories. Add recent proof of address when requested.
Digital onboarding often asks for a selfie or liveness check. Use a good camera and match names exactly to official filings.
Ownership evidence
Include the Certificate of Shareholding or equivalent proof of ownership. If shareholders are individuals, attach their ID pages too.
Constitution / Memorandum and Articles
Provide the company constitution or Memorandum and Articles of Association so reviewers can confirm signing powers and permitted activities.
Board resolution and when it matters
Some providers require a board resolution to appoint signatories and open the account; others waive this for online packages.
Where required, include a dated resolution signed by directors and a meeting minute or director’s written consent.
- Consistency: Ensure names, addresses and roles match ACRA records and the application form.
- Commercial proof: Add contracts, invoices, website or platform links if your model is not obvious.
- Single folder: Build one shareable pack to speed reapplications to a second-choice provider.
- Incorporation support: Using a professional incorporation service can reduce friction and raise the chance of quick success.
“Well-ordered documentation is the fastest route to a usable account and fewer compliance queries.”
Choosing an account that supports approval and day-to-day banking
Pick a product that matches your cash flows and the rest of the onboarding story—this makes your application more believable.
Minimum deposits and balance rules
Minimum initial deposit and ongoing minimums vary. Compare the opening sum with monthly thresholds and check how the average daily balance is measured.
Fees and real cost of ownership
Look beyond base monthly fees. Account maintenance, fall-below charges and annual fees add up. Also budget for wire fees, ATM or branch visit charges and transaction pricing for FAST/GIRO and SWIFT.
Transactions, online features and cards
Secure tokens, eAlerts, multi-user access and bulk payment tools reduce operational risk. Choose a solution that offers virtual and physical card controls and simple debit limits for spend management.
Multi-currency and integrations
Decide whether you need to hold foreign currencies, receive like a local with local details, or convert with transparent pricing. Prefer providers that integrate with Xero and payroll tools to speed reconciliation.
| Factor | What to check | Why it matters |
|---|---|---|
| Initial deposit | Amount and timing | Impacts liquidity and product fit |
| Average daily balance | Calculation method | Determines fall-below fees |
| Transaction fees | FAST/GIRO, SWIFT, ATM | Drives operating cost |
| Online features | Tokens, alerts, bulk pay | Reduces manual work and queries |
| Integrations | Xero, payroll | Saves time and improves compliance |
H2: singapore business bank account approval rate — what your choice of provider signals
The provider you pick sends a clear message to reviewers about the services you expect and the risk profile you present. Choose a full-service traditional firm and you signal intent for a primary SGD operating setup with branch access. Opt for a fintech and you signal a digital-first, multi-currency solution with lighter on‑ramps.
Traditional banks: broader services, stricter balance and fee structures
Traditional banks offer cheques, cash handling and in‑person support. That breadth comes with layered fees and tighter balance rules.
Applying to a full-service provider can increase scrutiny. Reviewers expect matching cash flows and governance for higher thresholds.
Non-bank providers: faster setup, fewer branch services, lighter minimums
Non-bank providers focus on fast online onboarding, low ongoing fees and minimal opening balances. They lack chequebooks and many branch rails.
They suit cross‑border sellers, platform merchants and teams needing multi‑currency tools. The trade‑off is fewer in‑person options and plan‑based pricing for advanced features.
- Signal effect: Provider choice aligns your profile with their risk appetite and reduces mismatch.
- Trade‑off: more services vs faster setup; branch access vs lower fees and automation.
- Who suits each: payroll‑heavy local SMEs may favour banks; export‑oriented firms may prefer fintechs.
| Category | Services | Onboarding |
|---|---|---|
| Traditional | Cheques, cash, branch | Slower, stricter checks |
| Non-bank | Multi‑currency, APIs | Faster, digital |
| Best fit | Choose by payroll, FX needs | Match profile to reduce delays |
Next: the following sections review “best for” scenarios and fee constraints so you can pick a product with fewer surprises.
Best for Singapore start-ups: OCBC Business Growth Account
For many start-ups, a recognised local growth product balances credibility with simple online onboarding.
Positioning: The ocbc business growth option suits founders who want a recognised relationship without routine branch visits. It works well for early payroll and local collections.
Fast online opening
The online banking flow uses Singpass for authentication. That shortens application time for new customers and helps complete KYC remotely.
Costs to watch
Key numbers matter to cash-strapped teams: an initial deposit of S$1,000 and a S$10 monthly fee (waived for the first 2 months).
If average balances drop below S$1,000, a S$15 fall-below fee applies. Closing within 12 months attracts a S$50 early closure fee.
Operational perks and limits
FAST/GIRO is free for payroll and bulk transfers. Up to 1% cashback on debit card spend helps offset small operating costs.
When multi-currency needs grow, add the OCBC Multi-Currency Business Account. Expect a S$120 annual charge and S$10/month if the growth account is closed.
| Item | Detail | Impact |
|---|---|---|
| Initial deposit | S$1,000 | Liquidity tie-up at opening |
| Monthly fee | S$10 (2 months waived) | Low recurring cost if balances held |
| Fall-below fee | S$15/month | Costs if average falls under S$1,000 |
| Multi-currency add-on | S$120/yr; S$10/month if no growth account | Higher fees when expanding FX needs |
Tip: Describe expected transactions and monthly volumes clearly when applying. Aligning your business growth narrative improves the odds of a smooth onboarding experience.
Best for digital-first SMEs: Airwallex Business Account
Airwallex suits digital-first SMEs that need global pay-in and pay-out capability without locking cash in minimums.
Positioning: This solution targets firms that trade across borders and want to avoid opening multiple local accounts or tying up funds with minimum balances.
Multi-currency capability
The platform lets users hold and manage 20+ currencies. You can receive local currency payments in supported markets and pay suppliers via local rails where available.
This removes routine FX conversions and simplifies reconciliation for multi-entity operations and ecommerce settlements.
Integrations and APIs
Airwallex integrates with Xero and other finance tools for automated reconciliation.
APIs allow custom payment flows and automated workflows, which helps teams scale transaction and spend management without manual steps.
Pricing and trade-offs
Entry plans typically have no initial deposit, no minimum balance and no monthly fee. International transfers over SWIFT can cost roughly S$20–35, while many corridors use cheaper local rails.
Check plan limits: features and fees vary by tier. Unlike a traditional bank, there are no cheque books or branch services, and advanced features sit behind paid plans.
“Describe your cross-border flows clearly when applying — aligning your use case with the product reduces queries and speeds onboarding.”
| Feature | Why it matters | Typical note |
|---|---|---|
| Multi-currency holdings | Reduces FX friction | 20+ currencies |
| Integrations | Speeds reconciliation | Xero + APIs |
| Pricing model | Impacts cost predictability | Plan-based; SWIFT S$20–35 |
Best for simple online banking with expense tools: Aspire Business Account
Aspire focuses on straightforward online setup and tools that keep day‑to‑day finances tidy.
What you get: a 100% online application, local payouts in multiple currencies and easy bulk payments for supplier runs or payroll‑style disbursements.
Day‑to‑day, the platform shows clear transaction history and simple expense categorisation. It integrates with common accounting software to cut reconciliation time.
Pricing basics and where costs grow
There is generally no monthly fee and no minimum balance, which helps avoid fall‑below charges for lean teams.
International transfers can add costs. Expect FX mark‑ups and transfers routed via SWIFT to start around US$8 depending on corridor and rail.
Cards and controls
Aspire issues virtual and physical cards. You can set spend limits and control card permissions to keep team spend visible and managed.
| Feature | Why it matters | Note |
|---|---|---|
| Online onboarding | Saves time and travel | 100% digital flow |
| Bulk payouts | Speeds supplier runs | Local rails supported |
| Expense tools | Reduces manual bookkeeping | Integrates with accounting software |
“Use Aspire as an operations account when local payouts and predictable domestic use matter most; move to a full FX specialist only if cross‑border volume grows.”
Best traditional option with no fall-below fee: CIMB SME Account
CIMB’s SME offering suits firms that want traditional services without the usual minimum balance traps. It removes the fall-below fee and often starts with a monthly fee waiver for the first 12 months. Verify current charges; some packages list S$0 initially and S$8/month after promotional months.
Fee highlights and local payments
Operational value comes from BizChannel@CIMB. This digital portal supports free local PayNow, FAST and GIRO payroll transactions and configurable eAlerts. These tools help SMEs manage cash without constant manual checks.
Limits and practical notes
It is SGD-only, so frequent foreign invoices or supplier payments can raise FX costs. International transfers may incur a fee after promotions (commonly up to around S$15 per transfer).
Cheque services and suitability
Where cheques still matter, a cheque book (circa S$25) and branch support make CIMB practical for legacy B2B workflows. For multi-currency needs, consider adding a fintech FX option later.
| Feature | Why it matters | Note |
|---|---|---|
| No minimum balance | Reduces cash strain | No fall-below fee |
| Local payments | Payroll and collections | PayNow/FAST/GIRO via BizChannel |
| Currency | Limits FX flexibility | SGD-only |
“As a traditional provider, CIMB still expects consistent documentation and a clear transaction plan when reviewing SME applications.”
Best for established SMEs that can maintain higher balances: UOB eBusiness Account
If your SME keeps steady operating buffers, the UOB eBusiness option pairs bank-grade controls with digital convenience.
Digital strengths: UOB Infinity handles payments and admin, while eAlerts give real‑time transaction monitoring and authorisation prompts. These tools reduce manual checks and improve day‑to‑day support.
Approval-ready preparation
Opening is multi-step. Expect collection of director and signatory details and possible requests for a board resolution depending on signing mandates.
Cost structure and thresholds
Typical requirements include a S$1,000 initial deposit, an annual fee around S$35 and a S$15 fall‑below fee if the average daily balance dips under S$5,000. Many packages waive the fall‑below fee for the first 12 months.
Match UOB to firms with regular payroll, supplier payments and steady local collections. If you cannot maintain the necessary balance, the account may feel approved but unsustainable due to recurring fees.
- Fit: established SMEs that can hold higher balance buffers.
- Operational note: strong digital features and familiar corporate banking services.
- Practical tip: outline expected monthly volumes when applying to speed review.
Best low-friction bank account for new owners: Maybank FlexiBiz Account
For founders seeking a simple, predictable opening, Maybank’s FlexiBiz offers a traditional setup without routine monthly charges.
What it is: a lower-friction, familiar option for new owners who want branch access, a debit card for everyday cash management and a straightforward pricing model.
How it keeps costs down
No monthly maintenance fee applies. Expect a typical minimum initial deposit of S$1,000 at opening.
Be honest about the manageable balance expectation: a S$10 fall-below fee is charged each month if the average daily balance drops under S$1,000.
Payments and rebates
Rebates for e-payments can apply if you maintain substantially higher average daily balances (examples cite thresholds around S$30,000). Treat these incentives as a bonus, not guaranteed savings.
International remittances
Outward transfers can incur commission, cable and agent fees. Price typical corridors before committing so your pricing forecast matches real costs.
- Cards & access: debit card for daily spend; branch support for occasional in-person needs.
- Currency: SGD base with an optional Foreign Currency Current Account for FX holdings.
- Tip: state local vs cross-border usage clearly when applying — it helps reduce queries and speeds review.
| Item | Typical detail | Impact |
|---|---|---|
| Initial deposit | S$1,000 | Ties up opening cash |
| Monthly fee | None | Low ongoing cost |
| Fall-below fee | S$10 if ADB < S$1,000 | Watch average daily balance |
“Clear transaction plans and realistic balance expectations make onboarding smoother for both customers and banks.”
Other contenders to consider for a bank account Singapore shortlist
Consider a curated set of alternatives that cover multi-currency holding, card-led spend and large‑bank relationships.
DBS Business Multi‑Currency (Starter Bundle)
Positioning: aimed at firms under three years, this starter bundle pairs a large‑bank relationship with multi‑currency holdings and online banking.
Cost caveat: branch service charges and overseas transfers are often priced as telegraphic transfers (commonly ~S$30 plus agent fees).
Wise Business
FX-first: transparent conversion and 40+ currency holds. A one‑time setup fee (commonly about S$99) unlocks full features and lower FX spreads.
YouBiz (YouTrip) & Revolut Business
Card-led solutions that suit teams needing multiple users, virtual and physical card controls and flexible plan pricing.
- Use these contenders as targeted second choices rather than applying everywhere.
- Match each option to your cash flows, card needs and expected cross‑border volumes.
| Provider | Strength | Note |
|---|---|---|
| DBS | Large‑bank trust, multi‑currency | Branch fees; SWIFT ~S$30+ |
| Wise | Transparent FX, many currencies | One‑time ~S$99 setup |
| Revolut / YouBiz | Card controls, multi‑user | Plan‑based pricing |
Tip: pick a second provider that matches your profile and only apply if the first choice is clearly unsuitable.
Side-by-side comparison: fees, balances, currencies, and transactions
Not all charges are obvious at signup; a side-by-side view exposes hidden costs.
Minimum deposit and tied-up cash
Initial deposit matters because it reduces usable cash. OCBC requires S$1,000 at opening. Maybank typically asks for S$1,000 as well.
Fintechs such as Airwallex and Aspire usually have no minimum balance on entry tiers. That frees startup cash but may limit certain rails or features.
Monthly, annual and fall-below fees
Compare fixed charges and promotional waivers. OCBC charges S$10/month (two months waived) and a S$15 fall-below if the average daily balance drops under S$1,000.
UOB lists an annual fee around S$35 and a S$15 fall-below if ADB
Local transfers and payroll suitability
For payroll and bulk disbursements, check FAST/GIRO allowances and per-item limits. Traditional providers typically include FAST and GIRO with predictable pricing, which suits regular payroll runs.
Fintechs support bulk local payouts too, often with simpler interfaces but tiered limits on free transfers.
International transfers and FX
When SWIFT is unavoidable, expect bank-style costs in the S$20–35 range plus possible agent fees. Fintech rails and local corridors can be much cheaper and faster for common corridors.
Tip: if you send cross-border payments often, model typical monthly transactions to compare true pricing versus sticker fees.
Cards, controls and multi-user access
Traditional debit cards offer branch-backed services and physical presence. Fintechs provide virtual and plastic cards with easy spend limits and user roles.
For growing teams, prioritise audit trails, multi-user permissions and card controls to avoid reconciliation friction and unauthorised spend.
- Match your most common three payments and three receipts to a product’s feature set.
- Factor waiver windows into year-two pricing — promotional waivers mask future monthly costs.
- Choose by cash needs: tied-up opening sums vs lower ongoing fees for digital-first operations.
| Item | Typical bank note | Fintech note |
|---|---|---|
| Initial deposit | Often S$1,000 (OCBC/Maybank) | Often none (Airwallex/Aspire) |
| Monthly/annual fee | S$10–35; waivers common first months | Often no monthly fee on entry tier |
| Fall-below fee | S$10–15 or higher if thresholds unmet (UOB higher ADB) | Rare on entry tiers; fees may appear at higher tiers |
| International transfers | SWIFT S$20–35 + agent fees; reliable | Local rails cheaper; SWIFT may be avoided |
Practical guidance: pick the product that matches your typical cash flows and transactions to avoid paying for unused features.
Application timeline and what to expect after submission
Once you hit submit, a sequence of verification steps usually defines when the account becomes usable.
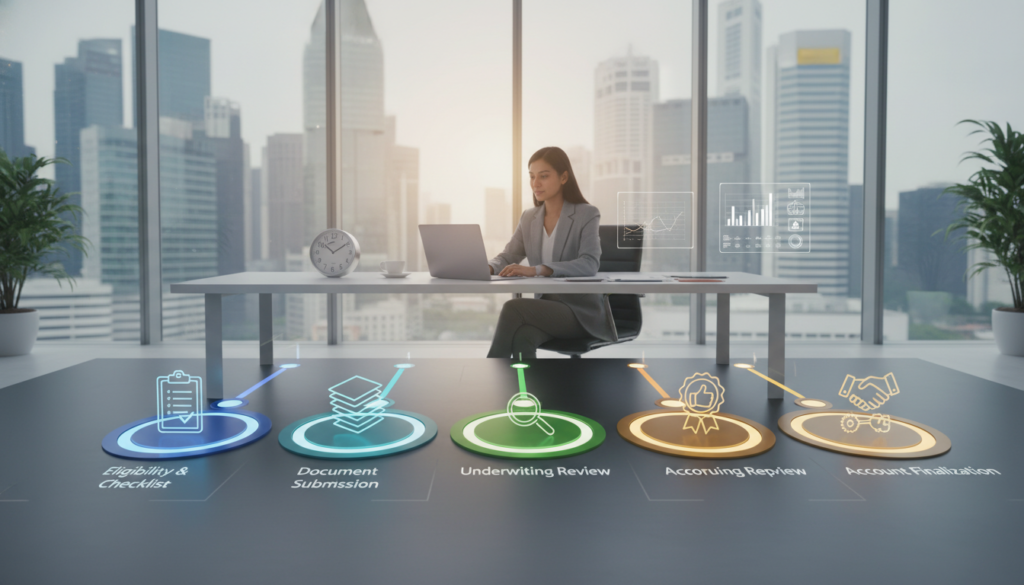
Online onboarding vs branch appointments
Online banking flows reduce scheduling delays and can complete identity checks in days. They work well for straightforward ownership and clear transaction plans.
Branch appointments add calendar time but may resolve complex questions faster. If reviewers ask for wet signatures or certified copies, a visit can shorten back-and-forth over several days.
Verification stages: KYC checks, clarifications, and activation
Typical stages run in sequence: identity checks for signatories, company verification, ownership screening and a compliance review of expected counterparties and flows.
Expect clarification requests. Reply with concise answers and supporting documents that match your original form to avoid repeat queries.
- Plan by stages, not promises — realistic timelines avoid surprises.
- Activation steps that affect time-to-use: token setup, enabling transfers, ordering cards and adding users.
- Build this timeline into launch planning so payroll, supplier onboarding and marketplace settlements are not delayed.
“Clear, consistent documents and quick replies are the fastest way to shorten the overall time.”
Practical steps to increase your approval chances (without guesswork)
Reduce uncertainty by preparing a tight, believable application pack that reviewers can verify at a glance.
Start with clarity: state your product or service, typical customers, payment methods and where funds originate and land. Keep this description short and consistent across forms, contracts and your website.
Align your documents, business description, and transaction expectations
Make every document tell the same story. Match ACRA or public filings, invoices and your online description.
Include sample invoices and a one‑page flow of money to show plausibility. That single page cuts follow-up queries.
Choose the right fit: start-up bundles, SME packages or multi‑currency solutions
Select a product that fits typical volumes. Start‑up bundles ease early growth, SME packages suit payroll-heavy firms, and multi‑currency solutions help cross‑border receipts.
Avoid fee and balance traps that trigger early closure or strain
Check minimums and fall‑below fees before you commit. Don’t pick an account with a balance threshold you cannot sustain—recurrent fees drain cash and harm long‑term success.
- Approval-ready checklist: short business description, sample invoices, director IDs, expected monthly volumes.
- Two-account mindset: use a local account for payroll and a fintech for FX if that matches operations.
- Operational hygiene: set alerts, limit user permissions and reconcile regularly to keep the account in good standing.
“Prepare concise, consistent documents and choose a product that matches real cash flows to speed onboarding and support future growth.”
How Osome can help you apply with banking partners
Osome supports founders by preparing a clean company file and making targeted introductions to digital and traditional partners.
Incorporation and compliance readiness matter because a tidy, correctly filed company profile reduces queries during KYC and speeds downstream checks.
Osome helps by ensuring statutory filings are up to date, organising director and shareholder documents, and producing a concise one‑page flow of funds. That single page shows where money comes from and where it goes, which often cuts follow-ups.
Introductions to selected partners
For eligible clients, Osome can introduce you to partners such as Aspire, Airwallex, Wise and UOB. Each partner suits different needs:
- Aspire — local operations and simple payouts;
- Airwallex — multi‑currency holdings and FX tools;
- Wise — transparent FX conversion and many currency lanes;
- UOB — traditional services with branch support and corporate rails.
What Osome does in practice
Osome prepares documents, advises on compliance, and shares a direct intro to partners that accept remote onboarding. This reduces errors and keeps information consistent across forms and public filings.
Note: introductions and guidance can lower friction but final decisions remain at the discretion of the provider. Partners may request extra evidence or decline applications.
Before an introduction, prepare: verified director/shareholder IDs, proof of address, a short business model note, and an estimate of typical monthly inflows and outflows. These items make your submission clearer and more credible.
| Service | Use case | How Osome supports |
|---|---|---|
| Aspire | Local payouts and payroll | Intro + prepared company pack for faster KYC |
| Airwallex | Multi‑currency receipts and FX | Intro + sample invoices and flow of funds |
| Wise | Transparent FX and low conversion costs | Intro + clear monthly volume estimates |
| UOB | Traditional rails and branch access | Intro + certified documents and signing mandates |
Final point: a guided approach reduces errors, improves consistency and can shorten the overall time spent managing compliance questions. Osome’s role is to prepare and introduce — the partner retains full discretion on the outcome.
Conclusion
The best path to a usable account is the one that mirrors your actual receipts, payments and growth plan.
Key takeaway: choose a product that matches your entity profile, expected transactions and cash runway. Prepare a consistent document pack, state plausible inflows/outflows and pick a provider whose features and pricing fit your year‑one needs.
Traditional banks suit SGD operating needs and broader services. Fintechs often win on speed, multi‑currency holdings and integrations, with trade‑offs such as cheque limits. Model year‑one and year‑two costs, including waiver expiry, fall‑below fees and transfer pricing, so the setup remains sustainable after initial months.
Shortlist 2–3 providers, prepare one high‑quality application pack and apply in sequence to meet launch timelines. Start with a workable business account now, then add specialised services as growth demands.
FAQ
What does the approval rate for a corporate bank account mean and why does it differ between providers?
How long does it take from application to an active account?
What common red flags cause rejections or delays?
Which documents are essential to improve my odds of approval?
Do all providers require local directors or shareholders?
What balance and fee rules should I watch for when choosing an account?
How do transaction fees and FX charges vary across providers?
What online features help with day‑to‑day cash management?
How do traditional banks compare with non‑bank providers in terms of services?
Why might I choose an OCBC Business Growth Account for a new company?
What advantages do Airwallex and Wise offer for cross‑border operations?
Which providers are best for low fees and simple online banking?
How should I prepare my application to reduce KYC friction?
What happens if I fall below an average daily balance requirement?
Can Osome help with account applications and paperwork?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.