Looking to bridge cash-flow gaps without a long-term loan—how can a flexible credit line help your business grow?
This page explains what a corporate overdraft is and why firms favour it as a working-capital tool rather than a long-tenure loan.
Think of the product as a revolving credit line: draw funds when needed, repay and redraw as cash flow permits. That makes it ideal for short-term cycles and seasonal demand.
Lenders typically assess a few pillars: incorporation status, operating history, local shareholding, existing banking relationship and whether guarantor support is available. Terms differ by bank.
DBS positions its solution as a revolving credit for growth while OCBC highlights collateral-free access for SMEs (terms apply) and notes guarantors may be requested.
Before you apply, check likely fees, document needs and the approval process so you can streamline submission. Check your eligibility and prepare your documents first.
Key Takeaways
- An overdraft facility is a revolving credit for short-term working capital.
- Lenders review incorporation, trading history and banking ties.
- Products vary: secured and unsecured options depend on profile.
- Draw, repay and redraw gives flexibility that a loan does not.
- Compare bank terms and confirm final facility details at application.
What a corporate overdraft facility is and how it supports business cashflow in Singapore
An overdraft facility provides a revolving credit line that your firm can draw on to fill short-term gaps. It sits on your business account so drawings and repayments happen through normal transactions.
Overdraft vs term loan
An overdraft is revolving: there is no fixed repayment schedule and you repay as cash allows. A term loan is drawn once and repaid in instalments and often costs less for long-term funding.
How interest is charged
Interest is charged only on the amount used and for the time it is outstanding. Many banks calculate this daily.
Example: S$100,000 x 6.5% x 30/365 = S$535 for 30 days (UOB-style calculation).
Secured and unsecured options
Secured facilities use assets such as property or fixed deposits as security. Unsecured lines depend on the business profile and may need personal guarantees.
| Feature | Overdraft | Term Loan |
|---|---|---|
| Repayment | Flexible, repay and redraw | Fixed instalments |
| Interest | Paid on amount used; often daily | Paid on full drawn principal |
| Best use | Bridging invoices, seasonal needs, emergency buffer | Long-term capex, fixed investments |
| Risk | Can be recalled; higher charges if exceeded | Lower rate for long tenure |
Good practice: treat an overdraft as short-term working capital, not a cure for ongoing losses. To compare market options, compare business overdrafts and match the product to your cashflow profile.
Corporate overdraft Singapore requirements: eligibility criteria lenders commonly apply
Lenders use a set of clear gates to judge whether a firm can access a short-term credit facility.
Business profile checks
Most banks expect a locally incorporated company with a minimum trading history. For example, OCBC often asks for at least two years of operations, while some lenders want three or more years.
Local shareholding thresholds
Ownership rules vary. OCBC may require about 30% Singaporean/PR ownership. Other banks can ask for higher local holdings — Standard Chartered has required 50% in some products.
Bank account and guarantor expectations
Many banks require an on‑bank account to manage the facility. DBS explicitly needs a DBS Business Account to use its overdraft offering.
Unsecured lines commonly need personal guarantees from directors or shareholders. OCBC notes guarantor(s) may be requested for collateral‑free options.
Indicative limits and what moves the needle
| Bank | Indicative amount | Notes |
|---|---|---|
| DBS | Up to S$500,000 | Depends on turnover and account conduct |
| OCBC | Up to S$200,000 | Two-year incorporation and local ownership often required |
| Standard Chartered | S$70,000–S$300,000 | May ask for 3 years’ trading and personal guarantees |
Tip: limits are set against turnover, cashflow stability and existing liabilities. Once you clear these gates, prepare documents and budget for fees to speed approval.
Documents, fees and approval considerations to streamline your application
Having the right paperwork and a clear fee plan speeds up approval and lowers friction.
Documents to prepare
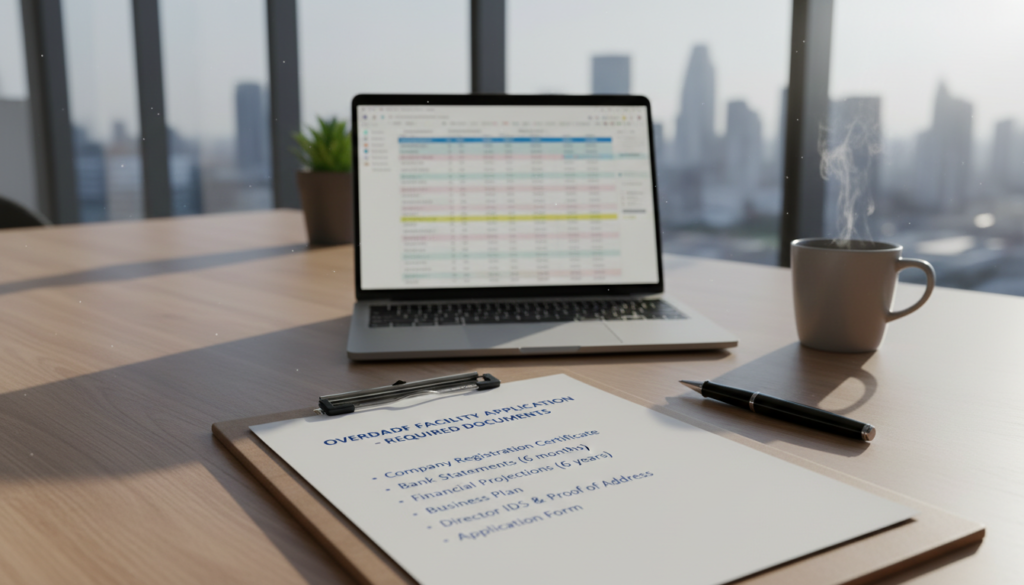
Gather MyInfo Business or Singpass access first; it shortens form completion and cuts uploads. Banks often claim the online form can take minutes when connected.
Prepare the latest two years’ profit & loss and balance sheet where requested, and provide six months’ bank statements if your account is with another provider.
Common fees to budget for
Expect a facility fee (percentage of approved amount with minimums), an annual fee, restructuring fees and excess or late interest charges.
| Fee type | Example | Notes |
|---|---|---|
| Facility fee | 1.99% (min S$500) | Standard Chartered example; confirm bank schedule |
| Annual fee | 1.50% (min S$500) | Charged yearly while the limit is active |
| Restructuring & late fees | S$250 / S$100 | Applied when terms change or repayments miss deadlines |
Pricing, channels and ongoing checks
Interest is typically charged daily on the utilised amount; an advertised board rate differs from effective cost after fees. Apply via MyInfo Business or ACRA search and expect bank follow‑up, credit checks and then documentation for account set‑up.
Many banks run annual reviews. Keep utilisation below limits and adjust the facility to match cashflow rather than running at full limit.
For workspace and financial planning, consider linking your application context to services such as serviced office rent.
Conclusion
Decide on a short-term facility only after matching the product to your receipts and payment rhythm. Use it when your business needs flexible access to funds for short-term cashflow and can repay irregularly as income arrives.
Remember the key gates: local incorporation and trading history, local shareholding levels, an on-bank account and possible guarantor support. Check these before you apply.
Compare total cost (interest plus fees), operational convenience (account rules, digital application) and risk terms (recall rights, penalties). Review MAS guidance on revolving facilities via MAS guidance on revolving facilities.
Next step: prepare documents, confirm eligibility gates and then approach your chosen lender to verify limits, fees and approval timelines. We help businesses assess fit, compile paperwork and handle lender queries to improve approval efficiency.
FAQ
What is a corporate overdraft facility and how does it support business cashflow in Singapore?
How does an overdraft differ from a term loan and when should each be used?
How is interest calculated on a business overdraft?
What are secured and unsecured overdraft options?
What are the main risks associated with an overdraft facility?
What eligibility criteria do lenders commonly require?
Are there local shareholding or ownership thresholds?
Do I need a business account with the lending bank to get a facility?
When are guarantors or personal guarantees required?
What indicative limits might banks offer?
Which documents should be prepared for an application?
What fees should businesses budget for?
How do interest rate and board rate affect pricing?
What are typical application timelines and channels?
How do annual reviews and monitoring work after approval?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.