Who ultimately controls a business — and why should that matter to you? This guide answers that pressing question with clear, practical steps for firms operating in Singapore.
This practical how-to guide explains what the internal Register of Registrable Controllers is, why it matters for anti‑money‑laundering and counter‑terrorist financing, and how to stay compliant in routine operations.
The article is written for founders, directors, corporate secretaries, finance and compliance teams, and in‑house counsel who manage governance and onboarding requests. It covers both ownership and control routes to identification, including indirect holdings and influence beyond share percentages.
Follow a simple workflow: learn the definitions, confirm whether your entity must keep the record, identify controllers, collect documents, keep data accurate, then meet filing and update timelines. The aim is to help you avoid fines and reputational harm while strengthening trust with banks and customers.
Key Takeaways
- Understand the purpose of the local transparency framework and who it affects.
- Maintain an accurate internal Register of Registrable Controllers and provide required information to the central repository.
- Identify controllers via ownership and control tests, including indirect influence.
- Collect verification documents and keep records up to date to meet filing timelines.
- Compliance reduces regulatory risk and supports stronger banking and customer due diligence.
Understanding ultimate beneficial ownership in Singapore
This section explains how to spot the real person behind complex shareholdings and who ultimately benefits.
What “ultimate beneficial owner” means in practice
Ultimate beneficial owner refers to a natural person who ultimately benefits from or controls an entity. FATF defines this as the person who ultimately owns or controls a customer or on whose behalf a transaction is made.
Beneficial owner vs legal owner
A corporate shareholder may be the legal owner on paper. The beneficial owner is the individual who profits or exercises real influence.
Common control tests
- Share percentage and the 25% threshold for beneficial ownership.
- Voting rights that decide outcomes at general meetings.
- Ability to appoint or remove directors, veto powers, or decisive contractual influence.
- Executive authority where someone effectively runs key decisions without heavy equity.
Mental model: ownership = percentages; control = power and governance rights. Both matter for compliance because banks and regulated firms routinely ask for these details during onboarding and reviews.
Where UBO details are used in AML, KYC and customer due diligence
Accurate ownership data is a linchpin for risk teams assessing transactions and onboarding customers. Regulators insist on clarity because knowing who benefits or controls an entity reduces the risk of money laundering and terrorism financing.
Why this matters to oversight
Regulators focus on ultimate owners to prevent misuse of corporate wrappers for illicit flows. Clear records help demonstrate compliance with anti‑money‑laundering rules and tax transparency.
How ownership details support KYC and monitoring
Information on beneficial owners feeds identity verification, screening, risk scoring and decisions on enhanced due diligence. It links suspicious transactions back to real people, revealing patterns consistent with layering or hidden control.
| Use | Operational benefit | Key data sources |
|---|---|---|
| Identity verification | Faster onboarding, fewer follow‑ups | Client info, ID documents, shareholder lists |
| Risk scoring | Targeted enhanced checks | Official registers, government databases |
| Transaction monitoring | Better detection of layering | Board resolutions, contracts, internal data |
FATF recommends corroborating multiple sources rather than relying on a single entry. Strong beneficial‑owner processes reduce enforcement risk, speed approvals and improve audit readiness.
Which entities must keep a Register of Registrable Controllers
The obligation to document controllers follows legal status, not turnover or trading activity, so many different entities fall in scope.
In scope: Local incorporated firms and any foreign company that registers locally must keep an internal record of their registrable controllers. This rule also covers LLPs and the newer VCC structure.
Smaller size or inactivity does not remove the duty. The law attaches to the entity’s legal form, so a dormant company or a newly formed business may still need to comply.
Common exemptions include listed issuers on prescribed exchanges and wholly owned subsidiaries of exempt entities. Confirm eligibility carefully before relying on an exemption.
Access and purpose
The internal record is not public. It supports regulatory and enforcement work while protecting personal data.
| Entity type | Typical obligation | Who may access |
|---|---|---|
| Local incorporated company | Must maintain internal record | ACRA, law enforcement |
| Foreign company registered locally | Same duty as local firms | ACRA, supervisory bodies |
| LLP / VCC | Obligation follows legal form | Regulators, authorised agencies |
| Listed issuer / exempt subsidiary | Possible exemption — verify status | Limited access, on case basis |
In‑scope entities must identify and record their registrable controllers and then follow prescribed maintenance and filing steps. For official guidance, see the Register of Registrable Controllers page.
ubo register requirements singapore companies
This paragraph summarises the legislative and supervisory sources that underpin controller reporting duties.
Key legal anchors
Companies Act and ACRA rules establish the obligation to keep an internal record of who has real control. Professional guidance from audit and AML bodies supports how to interpret those statutory duties.
Ownership threshold and wider control
Practically, the 25% test for shares or voting rights is the headline measure. However, control can exist without meeting that percentage when someone has decisive governance or executive authority.
Who counts as a registrable controller
The term covers natural persons with direct holdings and those reached via layered ownership or corporate intermediaries. Nominee arrangements and voting‑direction clauses can mean a different individual effectively controls outcomes.
Governance note: The internal record must be kept live. Identifying controllers requires mapping ownership, tracing to natural persons and documenting the nature of control clearly.
| Aspect | Practical test | Evidence to collect |
|---|---|---|
| 25% ownership | Direct shares or voting rights ≥25% | Share ledgers, share certificates |
| Indirect ownership | Control through intermediary entities | Structure charts, corporate filings |
| Control without threshold | Appointment rights, executive power | Agreements, board minutes |
How to identify registrable controllers and UBOs step by step
Create an ownership diagram that follows equity and decision lines. Start with a list of shareholders, map corporate layers and trace each chain until you reach natural individuals.
Mapping layered and nominee arrangements
Where a nominee appears on paper, identify who directs voting and who gains economic benefit. Do not stop at the nominee name; pursue the ultimate beneficiary.
Applying the 25% test
Apply the 25% threshold to both shares and voting rights. Check share classes and any agreements that alter economic and voting splits.
Assessing wider control
Review constitutional documents, shareholder agreements, reserved matters, veto and appointment powers. These often reveal true influence where ownership alone does not.
“Trace ownership and authority, then document the rationale for who is treated as a controller.”
- If no one meets the threshold, identify persons with ultimate effective control or executive authority.
- Adopt a risk-based approach: document assumptions, seek corroborating evidence and record decisions clearly.
What information and documents you need to collect
Start with a precise checklist of who needs to be recorded and which papers prove their control. Capture clear particulars for each registrable controller and keep supporting documents together.
Controller particulars to record
- Full name and any known aliases.
- Identification number or passport reference and date of birth.
- Nationality and current residential address.
- Concise statement of the nature of control (see examples below).
Proof and supporting records
Retain documents that corroborate the data: shareholder registers, up‑to‑date structure charts, constitutional documents and relevant board resolutions or agreements.
Handling foreign corporate shareholders
Trace ownership through incorporation evidence and share ledgers until you identify the natural person who ultimately owns or benefits. For non‑local files, standardise transliteration of names, match addresses carefully and note any changes to identity documents over time.
“Collecting accurate information and documents speeds KYC responses and strengthens regulator assurance.”
Maintaining the Register of Registrable Controllers
Keep the internal record accessible and organised so checks and audits take minutes, not days.
Where to keep the log and how to organise it
Hold the register at the company’s registered office or another prescribed location for prompt retrieval. Keep a clear folder structure and a digital backup with an immutable change log.
Recording nature of control and ownership
Record percentage bands for direct and indirect holdings and add short narrative entries for contractual or executive control. Use a standard template so percentage, legal route and the factual basis are visible at a glance.
Confirmations and annual notices
Send annual notices to each registrable controllers to verify particulars and supporting information. Reflect confirmed changes within 7 calendar days and keep documented chase attempts for non‑responses.
Good governance means assigning an owner—usually the company secretary or compliance lead—setting review intervals and keeping a change‑control log. Stale data after fundraising, transfers or new agreements is a common pitfall.
Inaccurate or incomplete records risk enforcement action, fines up to S$25,000 and operational delays such as bank onboarding hold‑ups.
Filing UBO information with ACRA and meeting timelines
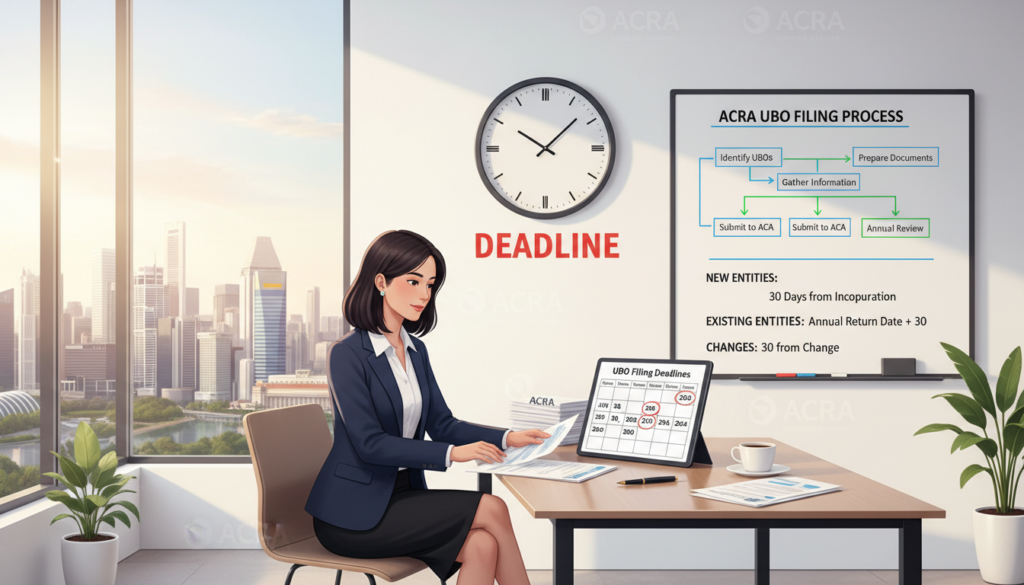
Timely submission of controller details depends on a disciplined internal process and clear corporate ownership of tasks. Start by updating the internal Register of Registrable Controllers and confirm all particulars before any external filing.
Order of operations and initial filings
Maintain the internal record first, then submit the corresponding information to ACRA’s central repository so the filed data mirrors internal evidence.
Newly incorporated entities normally submit initial particulars as part of early compliance steps. Existing entities should regularise historical controllers by confirming past entries and filing any missing information.
Timelines, dates and practical discipline
Guidance cites differing deadlines (for example, “within 7 calendar days after confirmation” versus “within 2 business days”), so check the latest ACRA regulations for your entity type.
Document both the date of awareness and the date of confirmation for each change to create an auditable trail.
Who owns the process and why speed matters
Directors should retain oversight while the company secretary or compliance lead executes the filing. Coordinate with group legal for multi-entity changes to ensure consistency of information across entities.
Fast, accurate filing reduces KYC delays, regulator queries and reconciliation issues during audits or bank reviews.
Ongoing monitoring, data quality and common compliance pitfalls
Regular data hygiene and review cycles are the backbone of a resilient AML compliance programme. That means simple, repeatable steps to keep ownership records accurate and auditable.
Keeping data accurate: avoiding stale records and entry errors
Standardise names, validate dates and addresses, and track source documents for each recorded person.
Adopt dual review for critical fields to reduce mistakes and keep a clear change log for audits.
Periodic reviews aligned to AML/CFT expectations
Schedule reviews after events that trigger stale data: share issues, class conversions, voting changes, nominee updates or restructures.
Higher‑risk sectors or material shifts in transaction behaviour should prompt more frequent checks.
Challenges for global groups: cross‑border thresholds and complex structures
Different jurisdictions use varied thresholds and definitions of control. Trace chains across multiple filings and reconcile internal records with shareholder ledgers and governance papers.
Failing to monitor reliably exposes a firm to missed obligations, enforcement risk, delays and reputational harm.
When to get help: consider corporate secretarial or AML advisory services to build a scalable monitoring approach and reduce the chance of costly fines.
Conclusion
Good beneficial‑ownership practice reduces risk and speeds routine business processes.
Maintain an up‑to‑date internal register of who controls the entity, identify the ultimate beneficial owner using ownership and control tests, and file verified particulars with ACRA promptly.
Beneficial ownership is ongoing governance, not a one‑off task. Update records after share moves, director changes or new agreements and keep supporting documents ready.
Practical steps to start today: map structure, identify controllers, collect ID and evidence, record concise particulars and review updates on a fixed schedule.
Do this well and your business gains faster bank onboarding, smoother deals and stronger stakeholder trust. Treat these obligations and regulations as normal corporate housekeeping supported by documented processes and periodic reviews.
FAQ
What does “ultimate beneficial owner” mean in practice?
How does a beneficial owner differ from a legal owner?
What control tests are commonly used to determine who ultimately owns or controls an entity?
Why do authorities focus on who ultimately owns or controls an entity?
How does identifying beneficial owners support risk assessment and transaction monitoring?
Which entities must keep a register of registrable controllers?
Are any entities exempt from keeping this internal register?
Who may access the internal register and is it public?
What are the key legal anchors for these obligations?
How does the 25% threshold operate and what about control beyond percentages?
What does “registrable controller” cover in practice?
How do you map ownership across layered or nominee arrangements?
How should the 25% threshold be applied to shares and voting rights?
How do you assess control by agreement, appointment rights or decision-making authority?
What if no individual meets the ownership threshold?
What controller particulars must be recorded?
What supporting documents should be retained to prove beneficial ownership?
How should foreign corporate shareholders be handled when tracing to natural persons?
Where must the internal register of registrable controllers be kept and how should it be organised?
How should the nature of control and percentage ownership be recorded?
What confirmations and annual notices are required to controllers?
What are the filing steps with ACRA and the central repository?
What are the expectations for initial filings by new and existing entities?
When must updates be submitted after changes in ownership or control?
How can organisations keep controller data accurate and avoid common errors?
What periodic reviews align with AML/CFT expectations?
What challenges do global groups face with cross-border thresholds and complex structures?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.