Curious how a hybrid business can protect partners while keeping flexibility?
This guide will walk you through singapore limited liability partnership registration from eligibility to post-filing compliance. It explains the online process via ACRA BizFile, the fees (S$15 for name approval and S$100 to register, total S$115), and practical timelines.
Expect most straightforward applications to be approved in about 15 minutes if details are correct and no referral occurs. Reserve a name for 120 days, secure partner endorsements, then download the Business Profile within 30 days after ACRA issues your UEN.
Before you start, decide if the structure fits your business, who will be partners and managers, and which registered office address you will use. Anticipate friction points such as referred names, missing consents and address rules to avoid extra days of delay.
Key Takeaways
- The guide covers the full singapore limited liability partnership registration journey, from eligibility to compliance.
- Name approval costs S$15 and reserves the name for 120 days; registration costs S$100 (total S$115).
- Most correct applications get fast approval via ACRA BizFile, often in about 15 minutes.
- Decide partners, managers and office address early to cut rework and delays.
- After approval you receive a UEN and must download the free Business Profile within 30 days.
Understanding an LLP in Singapore as a separate legal entity
An LLP combines partnership flexibility with corporate-style legal separation. It is governed by the Limited Liability Partnerships Act 2005 and functions as its own legal identity.
The term separate legal entity means the LLP can hold assets, enter contracts, sue or be sued, and continue despite changes in membership. That continuity helps client-facing businesses keep operations steady when partners come and go.
How limited liability protection works for partners
Under this model, partners are usually not personally responsible for the firm’s debts. The LLP generally shields personal assets from claims arising from another partner’s acts.
Be clear: limited liability does not protect a partner from their own wrongful act, professional negligence or misconduct. Each partner remains accountable for their personal errors.
Who an LLP suits best
This structure suits professional practices and partner-led firms that value flexible management and agreed profit sharing without full corporate formalities. It often feels simpler than a company for small teams.
- Good fit: consulting, accounting, medical and other professional teams.
- Decision cue: expect frequent partner changes? The LLP’s perpetual succession reduces disruption compared with a traditional firm.
For practical setup help and specialised LLP services, consult a local adviser.
LLP vs private limited companies: choosing the right structure
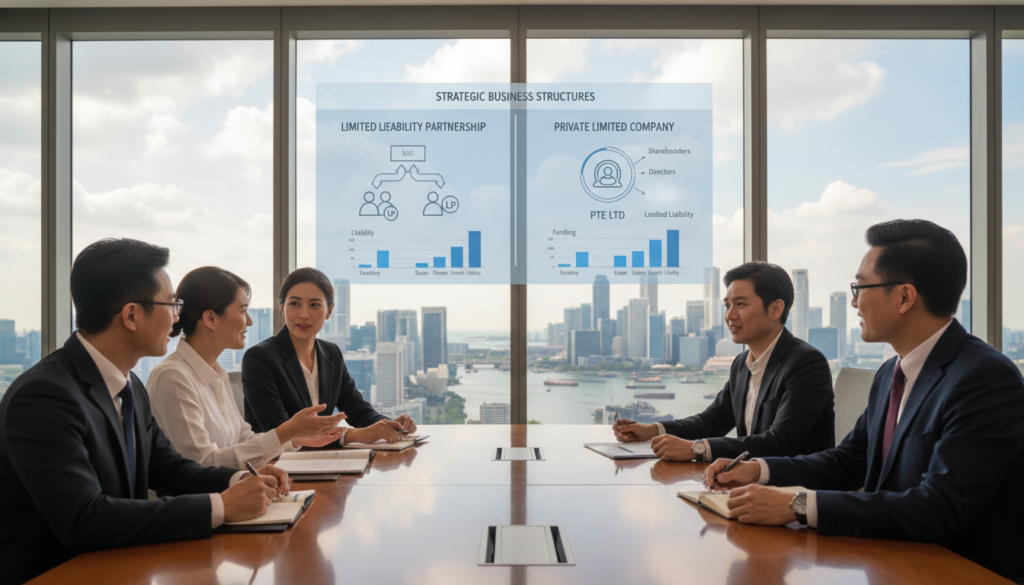
Your choice of entity drives how profits are taxed and how easily you can raise funds. Consider tax, compliance load and commercial perception when selecting a model for your business.
Tax treatment for individuals and corporate partners
Pass-through taxation means profits flow to each partner and are taxed at partner level rather than at the entity level.
Individual partners pay personal income tax on their share (rates up to 24%). Corporate partners are taxed at the corporate rate (17%). This mix can affect take-home income and planning.
Compliance, credibility and fundraising
An LLP usually has fewer formalities and no mandatory audit for small setups. A private limited company faces stricter compliance but often wins larger contracts.
Companies are easier to scale with equity funding because they can issue shares. That makes private limited companies a better fit for investors and fast growth.
| Feature | Partnership-style vehicle | Private limited companies | Impact |
|---|---|---|---|
| Tax | Pass-through to partners | Entity taxed; dividends taxed at partner level | Affects planning for individual and corporate partners |
| Compliance | Lower ongoing formalities | Higher reporting and corporate governance | Costs and administrative time differ |
| Fundraising | No shares; fundraising is harder | Can issue shares; attractive to investors | Limits or enables growth capital |
| Commercial perception | Suitable for small client work | Preferred for large tenders and long-term contracts | Affects win rates and partner requirements |
Quick decision checklist: define target clients, expected fundraising within the next few years, reinvestment horizon, and whether partner-level taxation suits your income plans.
Eligibility and requirements before you start
Start by confirming a few statutory requirements that affect who can be a partner and how the entity must be run.
Minimum partners and who can be a partner
The law requires at least two partners. Partners may be natural persons, local companies, foreign companies or another LLP. Choose partners carefully: their tax status and corporate form affect governance and future business planning.
Appointing a local resident manager
Every LLP must appoint at least one manager who is a natural person, aged 18 or above and ordinarily resident locally.
This manager provides local accountability. If all partners are overseas, ensure you name a resident manager to meet statutory expectations.
Registered office address rules
The LLP must have a physical registered office address in the jurisdiction for official correspondence. P.O. Boxes are not acceptable.
Foreigners and the role of a registered agent
Foreigners may be partners while overseas, but those without local digital access or SingPass often use a registered agent or authorised representative.
Use a corporate services provider to handle filings, ongoing compliance and to act as the local contact when needed.
- Confirm 2+ partners before filing.
- Ensure at least one resident manager (18+ and ordinarily resident).
- Secure a physical local office address (no PO boxes).
- Plan for a registered agent if founders are overseas or lack SingPass.
Documents and information to prepare for ACRA
Get your paperwork in order so the BizFile application can proceed smoothly in one session.
Start by gathering partner IDs, proof of address and a clear description of the intended business activity. Also prepare an operational agreement that sets out how the firm will run.
LLP agreement essentials and what happens without one
The LLP agreement is the operating backbone. It should cover profit sharing, decision rights, partner responsibilities, dispute resolution and entry/exit rules.
If you do not supply a tailored agreement, statutory defaults under the First Schedule of the LLP Act 2005 will apply. Those defaults may not match your commercial intent.
Identification, proof of address, and business activity details
Each partner and the resident manager must supply a valid passport or NRIC and a recent proof of residential address. Ensure details match exactly across all forms.
For the business activity, choose the most specific activity code and use a short, accurate description to reduce referral risk.
| Item | Why it matters | Example |
|---|---|---|
| Partner ID | Verifies identity for filings | Passport or NRIC |
| Proof of address | Confirms local contact and manager residence | Utility bill or bank statement |
| LLP agreement | Sets internal rules and avoids defaults | Profit split; voting; exit terms |
| Activity details | Avoids name or application referral | Specific activity code and short description |
Prepare basic internal records—capital contributions, expected profit allocation and minutes template—so post-filing compliance and tax work flows smoothly.
When you are ready to file the application, check the accuracy of the name and particulars to avoid correction filings. For official guidance use the ACRA guide.
Singapore limited liability partnership registration process via ACRA BizFile
Start the BizFile process by checking name rules and confirming all partner consents are obtainable within seven days.
Choosing and reserving your name for 120 days
Pick a clear, descriptive name that matches the planned business activity. Avoid restricted or sensitive words to reduce referrals.
Once ACRA approves the name on BizFile you pay S$15 and the name is held for 120 days. File the full application within this window.
Filing the application and timelines
Complete partner and manager particulars, the registered office address and statutory declarations. Pay the balance to finish the application (S$100 for the filing, making S$115 total).
Many correct applications get quick approval—often in about 15 minutes after payment. If a matter requires other-agency review, expect referrals that can take 14 days to 2 months.
Consents, outcomes and common delays
Every partner must endorse the application online within 7 days or the application will lapse. Missing consents are a frequent reason for restart.
After approval you receive the entity ID and can download the free Business Profile within 30 days. Common delay causes include sensitive activities, problematic names, inconsistent particulars or missing partner endorsements.
Essential steps right after registration
Within hours of getting your entity ID you should set up core records and apply for digital access to public services.
Setting up the Register of Registrable Controllers and same-day filing
llp must create a Register of Registrable Controllers (RORC) on the date of registration.
Identify individuals with significant influence or control, record their particulars, and complete the same-day filing to ACRA to meet the filing obligation.
Applying for CorpPass for government e-services
Apply for CorpPass so nominated users can access government services and complete future filings online.
CorpPass reduces administrative friction and secures access to key government portals.
Opening a corporate bank account and separating finances
Open a bank account in the business name early. Separating personal and business funds simplifies bookkeeping, tax work and partner distributions.
Banks usually ask for a Business Profile, proof of registered office, and partner or manager particulars — have these records ready to speed the process.
Licences and permits: checking GoBusiness before trading
Check the GoBusiness Licensing portal before you trade. Regulated activities need approvals and operating without licences risks penalties.
“Act on these first-day tasks straight away to avoid fines and administrative delay.”
- Create invoices and an expenses capture routine from day one.
- Keep partner drawings and contribution records to support future compliance.
Ongoing compliance and annual filing obligations for Singapore LLPs
Keep a simple annual calendar to meet mandatory filings and avoid penalties.
Annual solvency declaration and the 15‑month timeline
Within 15 months of incorporation the LLP must file a declaration of solvency or insolvency with ACRA. After the first filing, the same duty repeats at intervals not exceeding 15 months.
The filing typically carries a small fee (about S$30). Solvency means the firm can meet liabilities as they fall due; insolvency requires clear disclosure to protect creditors and partners.
Estimated Chargeable Income (ECI)
If IRAS issues a notice, file your ECI within 3 months of your financial year end. Use accurate accounting figures so the ECI aligns with your tax records and avoids revisions.
Partnership tax return and profit allocation
File Form P between 1 February and 18 April. Report gross income, allowable deductions and the profit or loss allocated to each partner.
Each partner then reports their share in their own tax return. Corporate partners account for allocations in their company tax filings at the applicable rate.
Record keeping and practical controls
Even without a mandatory audit, maintain full books: income, expenses and balance sheet support. Good records make tax time faster and reduce dispute risk.
- Nominate a responsible manager or partner to own compliance.
- Set internal deadlines one month before statutory due dates.
- Keep a shared tracker with key months and year‑end milestones.
| Obligation | Deadline | Notes |
|---|---|---|
| Solvency declaration | Within 15 months; then ≤15 months | Fee c. S$30; declares solvency status |
| Estimated Chargeable Income | Within 3 months of FYE (if notified) | Align ECI with accounting records |
| Form P (Partnership return) | 1 Feb – 18 Apr | Report income, deductions and partner allocations |
Keeping your LLP records accurate and updating ACRA on time
Keep core records up to date so your firm can trade, bank and contract without administrative friction.
Updating partner and manager changes within 14 business days
Statutory timing: notify ACRA of any change to partners or a manager within 14 business days of the effective date.
Plan internal workflows to collect consents, identity documents and proof of address fast. Typical updates that trigger a filing include changes in name, residential address, contact details, identification and cessation or admission of a partner or manager.
Updating RORC information within 2 business days
When you update your internal Register of Registrable Controllers, lodge the RORC update with ACRA within 2 business days. This quick step closes the loop between internal records and public filings.
- Adopt a clear change-management process: resolution or consent, collect particulars, submit filing, retain acknowledgement.
- Keep an internal log with the effective date, responsible person and proof that the filing was made.
- Assign a named compliance owner to manage filings and spot missing documents early.
Why this matters: counterparties, banks and regulators rely on current ACRA information. Stale records create delays for banking, tax and contractual checks and can lead to penalties for missed requirements.
Conclusion
Summing up the end-to-end process: confirm roles and prepare partner and business particulars, reserve the name, complete the ACRA filing, obtain endorsements and keep post‑approval documents for operations.
Core benefit: a limited liability structure gives clear personal asset protection while preserving partnership-style flexibility because the LLP is a separate legal entity.
Choose an LLP when pass‑through tax treatment and a light governance model suit your plans. Opt for a private limited company or company form if fundraising, issuing equity or market perception is central.
Keep simple compliance habits: same‑day RORC filing, on‑time annual declarations, accurate accounts and prompt updates for any change. Draft or refresh your LLP agreement, set an annual calendar and assign tax responsibilities now.
For service terms and governance references, read the terms and conditions.
FAQ
How do I register an LLP in Singapore?
What makes an LLP a separate legal entity?
How does limited liability protection work for partners?
Which types of businesses are best suited to an LLP?
How does an LLP compare with a private company for tax and fundraising?
What are the compliance and credibility differences between an LLP and a private company?
What are the minimum partner requirements and who can be a partner?
What is the role of a local resident manager and how is one appointed?
What are the requirements for the registered office address?
Can foreigners form an LLP and do they need a registered agent?
What documents should I prepare for ACRA?
Is an LLP agreement necessary and what happens without one?
How long can I reserve an LLP name and what are the naming rules?
What are the fees and typical approval timelines for filing?
What is the 7-day partner consent endorsement window?
What do I receive after approval and how long can I download the business profile?
What are common reasons an application is referred or delayed?
What steps must I take immediately after registration?
How do I open a corporate bank account for the LLP?
When must I file the annual solvency declaration and what is the timeline?
What are the tax filing obligations for an LLP?
How and when is the Partnership Income Tax Return filed?
Are LLPs required to have audits and keep accounting records?
How quickly must changes to partners or managers be updated with ACRA?
What about updating the Register of Registrable Controllers (RORC)?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.