Can one swift action spare a firm weeks of uncertainty and potential penalties?
This practical guide sets the scene for why a clear, step‑by‑step roadmap matters when mistakes surface after submission.
The term tax errors here covers GST slips, corporate income misstatements, omitted items, incorrect claims and mismatches between accounts and filed figures.
This article is written for SMEs and finance teams in Singapore. It explains how to assess an issue first, then the likely routes: amend GST via the F7 process where needed, update income filings (ECI or Form C variants), and address penalties.
Acting promptly and accurately usually limits disruption, reduces follow‑up questions and narrows exposure to penalties.
Processes and thresholds follow published IRAS guidance and common compliance practice. Seek tailored advice when facts are complex.
Key Takeaways
- Start with a calm assessment before choosing a remedy.
- Use GST F7 for relevant GST amendments and follow IRAS guidance.
- Amend income filings where figures differ from accounting records.
- Prompt disclosure tends to reduce enforcement risk and costs.
- Strengthen internal controls to prevent repeat issues.
Understanding tax errors in Singapore and why correcting them quickly matters
Year‑end pressure and weak review controls are common roots of reporting mistakes.
Rushed closes, missing source documents and misposted entries often create mismatches between ledgers and filed returns. In practice, weak review routines or unclear GST and income rules make small faults grow.
Typical mistakes across filing years include missed deadlines, inaccurate financial statements, overlooked incentives, incorrect GST reporting and poor bookkeeping. These slip-ups recur between periods when processes are inconsistent.
“An estimated Notice of Assessment may follow when returns are not filed; late payment attracts a 5% penalty and can compound monthly.”
Management consequences are tangible: unexpected bills, delayed refunds, time spent answering IRAS queries and weaker confidence from banks or investors.
- Incorrect returns can trigger information requests, reviews or audits when figures do not reconcile.
- Penalties and additional charges increase cash‑flow pressure, so early disclosure often saves money.
- Fixing an entry is more than editing a cell: quantify the impact, identify affected periods and keep an audit trail.
| Issue | Common cause | Immediate effect |
|---|---|---|
| Missing deadline | Poor calendar controls | Estimated NOA, penalties |
| GST misstatement | Misinterpreted rules | Output omissions, input misclaims |
| Inaccurate income | Misposted transactions | Reassessments, queries |
How to correct tax errors singapore company: assess what went wrong before you amend anything
Begin by pausing any amendment work and assembling a concise snapshot of the issue. A calm, documented assessment reduces the risk of making a second mistake while fixing the first.
Confirm the scope.
Confirm whether it’s GST, corporate income, or both
Decide if the problem affects GST, corporate income filings (ECI, Form C variants), withholding obligations, or a combination. This triage determines which filing pathways and IRAS forms apply.
Quantify the discrepancy and map affected periods
Measure the variance in dollars and the resulting tax effect: incremental output tax, disallowed input tax or additional assessable income. IRAS expects precise quantification, not rough estimates.
Match the misstatement to exact accounting periods and the original returns filed. Fixing the wrong period can create larger compliance problems.
Gather the right documents and prepare a short narrative
Assemble invoices, credit notes, contracts, bank statements, general ledger extracts, GST listings, fixed asset schedules and prior submitted forms in a clear folder structure.
Write a brief account of who, what, when and why, and state the remedial steps. This short narrative will support the Description of Errors and any corporate income explanation.
“A clear audit trail and concise explanation often reduces follow-up queries and speeds resolution.”
Correcting GST mistakes with IRAS GST F7 (Disclosure of Errors on GST Return)
Use the IRAS GST F7 when an earlier GST return contains figures that need formal revision.
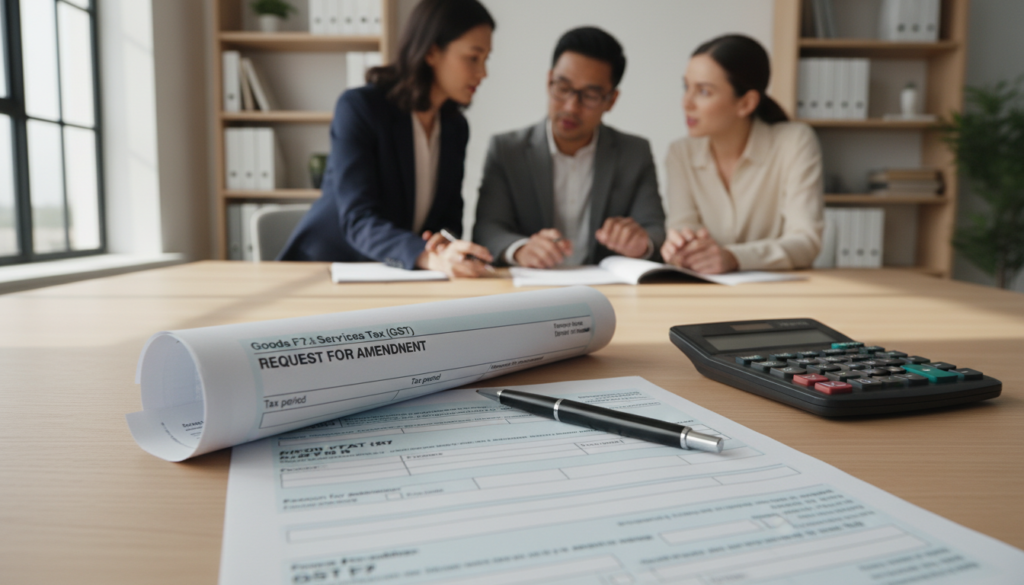
When an error appears in a submitted F5, F7 or F8, IRAS requires formal disclosure unless the administrative concession applies.
When GST F7 is mandatory and common filing faults
GST F7 is mandatory the moment you discover a mistake in a previously lodged return and the issue does not meet the concession criteria.
Typical mistakes include omitted sales that understate output tax, misclaimed input tax on non‑eligible items, and misreporting across boxes due to mapping faults in accounting systems.
Small‑error concession, net GST error and supplies test
Adjustments may be made in the next F5 only if both conditions hold: the net GST error across affected periods is ≤ S$3,000 and other box variances are ≤ 5% of total supplies (or taxable purchases if no supplies).
Calculate net GST error as additional output tax (Box 6) minus additional input tax (Box 7) across all affected periods.
Using the IRAS calculator and myTax Portal steps
Use the IRAS GST F7 calculator as a decision tool and retain the result in your working papers for governance.
Via myTax Portal: GST → “File GST Return / Edit Past Return” → Request GST F7. You must file the GST F7 within 14 days of the request or the request lapses.
Completing Boxes, consolidation and refunds
When filing, restate full revised figures for Boxes 1–17 and provide a clear Description of Errors that states root cause, affected periods and calculation basis.
If multiple accounting periods are affected, you may consolidate into one GST F7 for the last affected period of the year, provided the description explicitly covers all periods.
Overpaid GST can be claimed within five years from the end of the relevant accounting period. Support refund claims with credit notes and full quantification.
Payment and collection options
Payment may be collected via GIRO (ensure funds and limits), the 14‑digit payment slip, PayNow QR, AXS or internet banking. Choose the channel that avoids delays and further penalties.
“Document the calculator outcome and keep a clear audit trail for any GST F7 submission.”
Fixing corporate income tax errors and omissions (ECI and Form C-S/C-S (Lite)/Form C)
Mistakes in estimated chargeable income or the annual return can cascade unless records and computations tell a single, consistent story.
Two linked obligations must be managed: the Estimated Chargeable Income (ECI) and the annual corporate tax return (Form C-S, Form C-S (Lite) or Form C). Errors can arise in either stream and often come from misclassification, missed income items or unsupported deductions.
Deadlines and the filing difference
Plan around headline dates: paper submissions are due by 30 November; e-filing deadlines extend to 15 December for the Year of Assessment.
Electronic filing does not remove the need for complete accounts, schedules and supporting documents. E-filing simply changes the delivery method; readiness remains essential.
Aligning statements, computation and return
Follow a simple sequence: reconcile the trial balance, finalise audited or management financial statements, prepare tax computation adjustments, then populate the corporate return.
This chain ensures the narrative is consistent across documents and limits queries that lead to amendments.
IRAS response and practical steps if an estimated NOA arrives
Non-filing may prompt an estimated Notice of Assessment (NOA) based on prior information. That assessment is usually payable within one month and may be followed by information requests.
If an NOA is issued, prioritise lodging the outstanding return with correct computation and supporting documents, and manage payment while the matter is regularised.
“Submit complete workings and key documents promptly to shorten enquiry cycles.”
Supporting documents that matter:
- Financial statements and trial balance
- Detailed tax computation and adjustment schedules
- Capital allowance and loss schedules
- Key contracts, invoices and bank statements
| Issue | Usual cause | Immediate action |
|---|---|---|
| ECI variance | Forecasting or posting differences | Reconcile and amend ECI if material |
| Form C inconsistencies | Misclassified revenue/expenses | Prepare corrected return with workings |
| Non-filing | Missed deadline or oversight | File immediately; expect estimated NOA |
Engage professional services where adjustments span multiple years, governance is weak or documentation is incomplete. A tax agent or accountant can speed resolution and improve ongoing compliance.
Managing penalties for incorrect returns, late filing, and late payment
A single missed deadline can trigger a chain of enforcement steps that drain time and cash.
Late filing consequences: composition offers, summons, and escalation
Failure to file may start with a composition offer (usually not exceeding S$5,000 per offence). If returns remain outstanding, IRAS can issue an estimated Notice of Assessment and request director information.
Persistent non-compliance can lead to a summons or court action, with fines or other sanctions on conviction. This progression creates director time cost and reputational risk for businesses.
Late payment mechanics and modelling exposure
Unpaid amounts attract an immediate 5% penalty if not settled by the NOA due date.
If the sum remains unpaid 60 days after that 5% is applied, an additional 1% per completed month may be imposed, up to 12% in total. Finance teams should model these layers when forecasting cash flow and payment exposure.
Translating “up to 200%” and “up to 400%” into practice
Penalties of up to 200% typically apply where undercharged income arises without evidence of intent. Where deliberate evasion is suspected, sanctions can reach up to 400% plus possible fines or imprisonment.
Agent appointment risk and operational impact
IRAS may appoint agents such as banks or lawyers to recover outstanding sums. This can restrict access to funds and disrupt normal business operations beyond the immediate legal consequence.
Appealing for waivers via myTax Portal
Requests for waiver are submitted through myTax Portal and generally need the outstanding filing and payment completed, a clear history of compliance, and a concise explanation with supporting documents.
- Control the three buckets: incorrect returns (quality), late filing (process), late payment (cashflow).
- Act swiftly: pay or arrange payment, file missing returns, and prepare a short written explanation with evidence.
- Maintain a clear internal log of remedial and preventive measures to strengthen any waiver request.
“Prompt, documented action and better governance improve the chance of mitigation.”
For official guidance on penalties, see the IRAS page on penalties for errors in tax returns.
Using IRAS Voluntary Disclosure to reduce penalties and stay compliant
Proactively notifying IRAS can limit penalties and show a genuine commitment to compliance.
Where the Voluntary Disclosure Programme (VDP) applies: the scheme covers income, gst, withholding tax and stamp duty. It is intended for parties that come forward before an enquiry or audit begins, and can regularise past returns across multiple tax types.
Timing and penalty outcomes
Disclosures made within the one‑year grace period from the statutory filing deadline may attract no penalty if qualifying conditions are met.
After that grace period, voluntary disclosure can still reduce penalties. In practice, late undercharged income may see an example rate such as 5% per year late, subject to IRAS assessment.
Submitting a voluntary disclosure
Use the myTax Portal “Revise/Object to Assessment” e‑service to lodge the disclosure and receive acknowledgement.
Follow up by emailing supporting information to ctmail@iras.gov.sg. Include reconciliations, calculation schedules, invoices/credit notes and a short narrative explaining root cause and remedial steps.
Related parties and group disclosures
Ensure consistency where related parties are involved. Align intercompany schedules and provide cross‑references to reduce follow‑up queries.
Strengthening governance
Tax Governance Framework (TGF) and CTRM status offer practical benefits. Approved TGF submissions may grant a one‑time extended grace period, while CTRM recognition can allow a one‑time waiver for prior‑year disclosures.
“Voluntary disclosure supports a culture of compliance and, despite upfront work, often reduces future disruption.”
- Place clear reconciliations and supporting documents with your disclosure.
- Act early: timing materially affects penalty outcomes and follow‑up workload.
- Document improved controls as part of the submission to strengthen mitigation prospects.
Preventing repeat tax errors: controls, reconciliations, and record-keeping for Singapore companies
A control-first approach reduces the need for remedial work and limits exposure.
Start with a simple governance frame: systems, people and a review cadence.
Building a tax calendar and reminders
Create a calendar covering GST cycles, ECI and annual tax filing, payment due dates and internal close deadlines.
Assign clear responsibility for each item and set automated reminders for preparers and approvers.
Improving bookkeeping and retaining records
Use a consistent chart of accounts and strict classification rules for revenue and expenses.
Perform timely bank reconciliations and keep customer and supplier master data controlled.
Retain key documents and records for at least five years and adopt searchable digital filing so audits are quick and evidence is complete.
Internal GST reviews, reconciliations and training
Run periodic checks on output completeness and input eligibility, sample invoice testing and staff refreshers.
Reconcile financial statements with tax returns using tie-out schedules for revenue, expenses, assets and GST control accounts.
Staying current and documenting related-party pricing
Subscribe to updates, attend seminars and engage professional services for high-risk areas.
Keep intercompany agreements, pricing rationale and benchmarking analyses to support allocations for related parties.
“Preventive controls and clear records make compliance routine rather than crisis management.”
For practical year‑end planning guidance, see year‑end tax planning strategies.
Conclusion
Swift triage, precise numbers and the right filing route shorten enquiry cycles and cut costs.
Start by identifying the affected return and periods, quantify the impact, then file through the proper channel—GST F7 for GST issues or the relevant corporate amendment—and document your rationale clearly.
Act now, as early action reduces escalation, lowers time spent on reactive queries and helps protect cash flow from compounding penalties and failure-driven enforcement.
Remember that GST corrections need specific windows, revised box entries and supporting documents, while corporate filings must match accounts, computations and submitted returns.
Voluntary disclosure can limit penalties when complete and timely. For multi-year or complex cases, seek a professional service to coordinate remediation across finance teams.
FAQ
What immediate steps should a business take when it identifies an error in a corporate tax return?
When is an IRAS GST F7 required and how quickly must it be filed?
What kinds of GST mistakes commonly trigger adjustments?
Can small GST errors be adjusted in the next GST F5 return instead of filing F7?
How should companies calculate the net GST error and apply the 5% supplies test?
What is the process for claiming refunds for overpaid GST?
How are payments handled once an error is disclosed — what options are there?
What deadlines apply for correcting corporate income tax returns such as ECI and Form C/C‑S?
How should companies align financial statements with tax computations and returns when correcting income tax errors?
What penalties apply for late filing and late payment of taxes?
How does IRAS calculate penalties for undercharged tax, and what do “up to 200%” or “up to 400%” mean?
Can IRAS recover unpaid corporate tax from third parties or appointed agents?
What options are available if a business wishes to appeal or request a waiver for penalties?
When should a business use the IRAS Voluntary Disclosure Programme?
What are the timing rules for voluntary disclosure and how do they affect penalties?
How do you submit a voluntary disclosure via myTax Portal and what supporting documents are needed?
What internal controls help prevent repeat mistakes in GST and corporate tax reporting?
How important are reconciliations between financial statements and tax returns?
What basic transfer pricing documentation should related‑party transactions include?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.