Curious which support option truly helps your SME most — immediate cash or lower taxable income?
This buyer’s guide helps businesses choose what replaced the old PIC after YA2018. It explains that there is no single fix; rather, a menu of programmes targets different aims: cash support, tax deductions, capital allowances, workforce training and market entry.
The guide previews key programmes such as EIS (YA2024–YA2028), Investment Allowance, PACT, SFEC and DTDi. It maps each to common spending: software, equipment, training, IP and overseas development.
Eligibility and administration vary by agency — IRAS, EDB, Enterprise Singapore and SkillsFuture Singapore — and timing matters: some require pre-approval while others are claimed via annual tax filing. Compliance is part of choosing: keep records, document projects and note the effect of electing cash conversion under EIS.
Key Takeaways
- Think of the post‑PIC options as a menu, not a single programme.
- Decide whether you need immediate cash or tax relief that lowers chargeable income.
- Match EIS, IA, PACT, SFEC and DTDi to your spending profile and timelines.
- Check eligibility and pre‑approval rules with the relevant government agency.
- Maintain clear records and project evidence if you pursue claims or cash conversion.
Why businesses needed PIC alternatives in Singapore
When PIC expired after YA2018, firms faced a clear gap: a single, generous incentive that once covered many types of qualifying spend disappeared.
What changed after the old scheme ended
The PIC once offered broad enhanced relief for staff training, equipment and software. Its lapse left many SMEs unsure how to claim relief for similar outlays. The post‑PIC period moved away from one umbrella model toward targeted supports.
What replacement measures mean today
Think of today’s options in buyer terms: tax deductions reduce taxable profits, allowances provide extra write‑offs, grants offset project costs, and credits reimburse eligible spend after approval.
How Budget 2023 reshaped incentives
Budget 2023 introduced the Enterprise Innovation Scheme (EIS) as the most PIC‑like option for YA2024–YA2028. EIS targets five qualifying activities and offers enhanced tax deductions and allowances, plus a cash payout for firms with low profits.
Why this matters: careful timing, vendor contracts and records can cut your tax bill or boost near‑term cash flow. The best alternative depends on whether your business is profitable, buying capital assets, working with larger partners, or entering overseas markets.
Next: a side‑by‑side comparison will help you shortlist which option fits your plan.
productivity and innovation credit singapore replacement schemes explained
Compare the principal support routes so you can match your planned spend with the right application process.
Quick comparison of main options
EIS is best for training, IP and local R&D where enhanced tax deductions or a cash payout matter.
Investment Allowance (IA) suits heavy equipment and factory build‑outs that are capital in nature.
PACT supports co‑innovation with larger partners, while SFEC offsets out‑of‑pocket transformation and training costs.
DTDi targets overseas market activity and e‑commerce campaigns; some activities are approval‑free up to S$150,000, while campaigns need prior approval per country and are limited to one year.
Who manages what
| Programme | Administrator | When to engage |
|---|---|---|
| EIS | IRAS (claims at filing) & SkillsFuture Singapore (training alignment) | File with tax return; check training alignment early |
| Investment Allowance | EDB | Apply for approval before incurring capital expenditure |
| PACT / DTDi | Enterprise Singapore | Seek approvals before market or co‑innovation activities |
Key decision factors
Profitable business tend to prefer enhanced tax deductions. Low‑profit firms may value cash support such as EIS payouts or SFEC reimbursements.
Match capital versus operating spend: capital equipment points to IA; staff, software and R&D point to EIS.
- Check pre‑approval windows and year assessment timing.
- Estimate cash flow timing — tax savings come at filing while grants reimburse after milestones.
- Shortlist by alignment with your resources, costs and market plan before committing to vendors.
Enterprise Innovation Scheme as the modern successor to PIC
EIS is the closest modern successor to PIC. It targets five defined stages across the innovation value chain, from early R&D to protecting rights and building skills.
How the enhanced relief works
Enhanced tax deductions up to 400% mean qualifying costs can be multiplied for tax relief. Rather than a single‑for‑one deduction, a multiplier increases the allowable write‑down against taxable profit.
What counts as qualifying expenditure
Qualifying expenditure covers direct spend on r&d in Singapore, fees for intellectual property registration, acquisition or licences of qualifying IP rights, SkillsFuture‑aligned training, and small polytechnic or ITE project fees.
| Feature | Detail | Limit |
|---|---|---|
| YA window | Applies YA2024–YA2028 | Five years |
| Enhanced rate | Up to 400% deduction/allowance | Per qualifying activity rules |
| Cash conversion | 20% non‑taxable payout option | Up to S$100,000 spend → S$20,000 payout per YA |
When cash beats tax relief
Early‑stage firms or those with low chargeable income may prefer the 20% non‑taxable cash payout for liquidity. Note conversion is irrevocable; converted amounts cannot also be claimed as deductions.
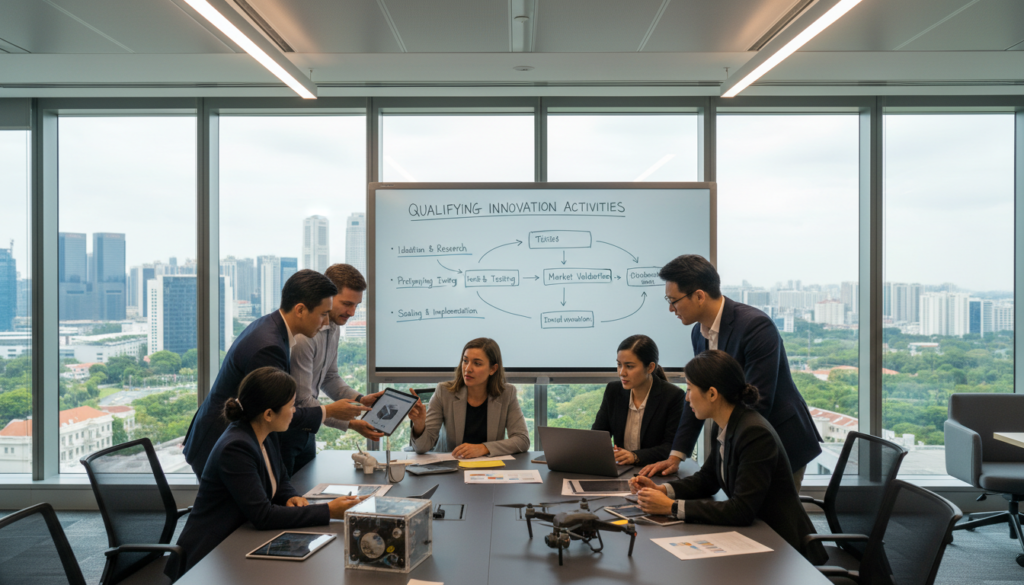
Eligibility checks and qualifying innovation activities under EIS
Start by verifying that your firm is actively trading in Singapore and that planned costs map to an EIS qualifying activity.
Quick pre‑check flow
- Confirm Singapore registration and active operations during the basis period.
- Match planned spend to a qualifying activity under EIS (r&d, IP, SkillsFuture‑aligned training, etc.).
- Decide whether you will claim enhanced tax deductions or elect the cash payout route.
Entity types and operating realities
All Singapore‑registered entities — companies, partnerships and sole traders — can claim enhanced deductions if they carry on active operations and have incurred qualifying expenditure in the relevant basis period.
For the cash option, the firm must be operating in a non‑winding down state; entities under judicial management, in liquidation or purely investment holding do not qualify.
Minimum local headcount for the cash payout
To be eligible for the non‑taxable cash conversion, businesses must employ at least three full‑time local staff.
Each local employee must be a Singapore Citizen or PR paid at least S$1,400 per month and employed for six months within the basis period. Keep consistent payroll and CPF records to evidence compliance.
Common grey areas and documentation
Software subscriptions often do not qualify unless the spend is for bespoke development that produces new capabilities. Distinguish routine automation upgrades from project work that tests hypotheses and iterates — only the latter is typically qualifying.
Staff costs must be apportioned when personnel split time between qualifying project work and normal operations. Consumables need a clear project link to be treated as qualifying expenditure.
Project records matter: scopes of work, R&D hypotheses, testing logs and deliverables create the qualifying narrative if IRAS reviews the claim.
Choosing deduction versus cash payout
High chargeable income usually favours enhanced deductions; they reduce tax at the marginal rate. Firms with low profits or tight cashflow may prefer the 20% non‑taxable cash conversion despite its lower nominal value.
Practical tip: ring‑fence qualifying costs and assign accounting codes now. This reduces the risk of over‑claiming and simplifies an audit trail.
| Check | Requirement | Why it matters |
|---|---|---|
| Entity status | Registered and actively trading in Singapore | Only active businesses can claim enhanced deductions |
| Headcount (cash) | ≥3 full‑time locals, ≥S$1,400/month, 6 months | Determines cash payout eligibility and avoids disallowance |
| Expenditure type | Must be incurred qualifying r&d, training, IP cost or aligned activity | Ensures spend is eligible for enhanced tax relief or cash |
| Documentation | Scopes, testing logs, invoices, payroll and contracts | Supports claims during IRAS review |
For full details on qualifying rules and to check claim mechanics, consult the official guidance at EIS on the IRAS site.
How to claim EIS without compliance surprises
A clear claims plan prevents last‑minute errors at year‑end and keeps finance teams audit‑ready.
Where EIS sits in the annual filing
Enhanced deduction entries are part of the corporate return. Record them in Form C‑S or Form C when you file.
Use IRAS digital services for submission. Keep attachments organised so reviewers see a consistent audit trail.
Evidence to keep for seven years
Retain supplier invoices, signed contracts or SOWs, training enrolments, IP filing receipts and project logs that show the business purpose.
Label folders by year and by qualifying activity. This reduces search time if IRAS requests supporting documents.
What is lost after electing the cash payout
The 20% cash conversion is irrevocable and only one application is allowed per year of assessment. Once you elect conversion, that expenditure can no longer be claimed as tax deductions or allowances.
Before you apply via the “Apply for EIS Cash Payout” digital service, run a simple comparison of tax saved versus cash received.
Common compliance surprises
- Missing local headcount conditions for the payout.
- Insufficient linkage between invoices and the qualifying project.
- Mismatched dates between invoice, payment and basis period.
Investment Allowance for capital expenditure-heavy projects
When firms plan major capital works, the 100% Investment Allowance is often the most relevant fiscal tool.
What IA does: The Economic Development Board (EDB) administers a 100% Investment Allowance that can provide up to a full tax exemption on qualifying fixed capital expenditure for approved projects.
How it sits with capital allowances: IA is an additional relief for approved projects, not a replacement for normal capital allowances. Use IA where large capital outlays would otherwise take years to write off.
What typically qualifies
- New productive equipment and automation lines.
- Factory construction or property works in Singapore.
- Acquisition of patents, technical know-how or intellectual property tied to the project.
- Specialised engineering or facility development that upgrades capacity.
Timing, approval and commercial limits
EDB pre-approval is the single biggest constraint: apply before you incur the expenditure. Procurement, vendor contracts and payment schedules must reflect the approval timing.
| Feature | Detail |
|---|---|
| Project window | Typically five years; extensions possible up to eight years |
| Cap | Support capped at S$10 million |
| Availability | Scheme extended to 31 March 2026 |
Practical buyer checklist
- Prepare a business case showing expected tax and cash benefits.
- Gather equipment specs, vendor quotes and realistic timelines.
- Seek EDB approval before signing major purchase orders to avoid disallowed costs.
PACT scheme for co-innovation and capability transformation with larger partners
PACT links larger buyers with smaller suppliers to fund cooperative development that upgrades capabilities and market readiness.
What PACT supports
Supported costs include equipment, materials, testing, professional services, and manpower. SMEs may get up to 70% funding for manpower, software, materials and services, and about 50% for equipment.
Common use cases in Singapore
Typical projects cover supplier development, technology transfer, precision engineering upgrades, additive manufacturing trials, and joint product or process development. These activities help SMEs access larger market chains and technical know‑how.
Funding, disbursement and project structure
Proposals are often led by the larger partner and administered through Enterprise Singapore or EDB engagement. Funds are paid on milestone achievement, not as full up‑front grants.
- Prepare detailed workplans, cost breakdowns and measurable deliverables.
- Define IP ownership, confidentiality, test criteria and acceptance milestones early.
- Consider cross‑border services, royalties and potential withholding tax when planning.
SkillsFuture Enterprise Credit and other complementary levers for workforce and market expansion
For many small firms, SFEC acts as a near-instant offset to residual project costs after other grants apply.
SFEC basics
SFEC provides a one-off S$10,000 payment. Eligibility is checked automatically via the Business Grants Portal or SkillsFuture for Business. It can offset up to 90% of eligible out-of-pocket costs on top of other programmes.
Plan two spend buckets
Separate budgets into enterprise transformation and workforce transformation. Enterprise spends target market reach, digital set-up and advisory fees. Workforce spends cover training, job redesign and upskilling.
What to expect after 2026
Budget 2025 signals a move to a digital wallet model from H2 2026. This will change reimbursement timing and internal budgeting. Plan cashflow now to avoid gaps when the model launches.
DTDi for overseas market activity
The Enhanced Double Tax Deduction for Internationalisation supports qualifying overseas expenses. New coverage includes e-commerce campaigns: business advisory, account creation, content creation and product listing fees.
| Feature | What it covers | Key constraint |
|---|---|---|
| SFEC | S$10,000 one-off; 90% offset of eligible costs | Automatic eligibility checks via Business Grants Portal |
| DTDi e-commerce | Advisory, account setup, content, listings | Prior Enterprise Singapore approval; one-year, per-country limit |
| DTDi no-approval tier | Smaller qualifying expenses | First S$150,000 may not need prior approval |
Practical tip: focus resources on chosen markets first. Ensure vendor invoices describe services clearly to meet approval and documentary tests for tax relief.
Conclusion
Decide first whether your firm needs near‑term cash or longer‑term tax relief to fund upcoming projects.
Match profitability and purpose: start by checking profit position, headcount rules for the cash option, and the type of spend — development, capital assets, partnerships, training or market expansion.
Treat the PIC replacement as a portfolio: EIS offers up to 400% enhanced deductions and a 20% non‑taxable cash payout (capped at S$20,000 per YA); IA needs EDB pre‑approval and is capped at S$10m to 31 March 2026; PACT pays by milestone; SFEC gives a S$10,000 top‑up and will move to a digital wallet from H2 2026; DTDi covers e‑commerce with prior Enterprise Singapore approval per country for one year.
Document projects, keep records for seven years, and allocate costs clearly to protect claim value. Plan approvals before committing resources and run a scheme‑fit review for your next 6–18 months of work. Speak with a Singapore tax professional or grant specialist to ensure claims are optimised and defensible.
FAQ
What replaced the Productivity and Innovation Credit (PIC) after it ended?
Why did businesses need PIC alternatives?
What does the Enterprise Innovation Scheme (EIS) cover?
How do the enhanced tax deductions under EIS work?
When is the cash payout option preferable to taking a tax deduction?
Which agencies administer the different schemes?
How do I decide between EIS, Investment Allowance and other options?
What records should businesses keep when claiming EIS?
Are software upgrades and automation improvements claimable under EIS?
What are the timelines and caps for EIS benefits?
How is an EIS claim filed in corporate tax returns?
What becomes non‑claimable after electing the cash payout?
How does the Investment Allowance complement capital allowances?
What does the PACT scheme fund and when is it suitable?
What is SkillsFuture Enterprise Credit (SFEC) and how does it interact with other incentives?
How can businesses use DTDi for overseas market activities?
Are there upcoming changes I should plan for?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.