Thinking of launching a business in Singapore — but unsure which rules will bite you first? This guide answers that question with a clear, practical path. It sets out the essentials of singapore company compliance for foreigners and what each overseas founder must budget for in days and documents.
Expect digital-first registration via ACRA, but not a set-and-forget outcome. You will learn the incorporation steps, statutory appointments, tax filing obligations with IRAS, and ongoing governance under the Companies Act.
Who this guide helps: non-resident founders, foreign parent entities expanding in the city-state, and overseas directors or shareholders. It shows how to end up with a compliant setup and a workable annual calendar.
Note the practical constraint many miss: you cannot self-register. You must engage a registered filing agent, so choosing the right provider is part of compliance. For a full step-by-step walkthrough, see this detailed registration resource at company registration guide.
Key Takeaways
- Registration is digital through ACRA, but governance duties stay with directors.
- Foreign owners can hold 100% of shares, yet must use a registered filing agent.
- This guide covers pre-incorporation planning to annual ACRA/IRAS milestones.
- Prepare key documents early: name, SSIC code, director/shareholder details and address.
- Budget timelines and fees in days and months, not vague estimates.
Why Singapore remains a top base for foreign-owned companies
Non-resident entrepreneurs favour this hub for its predictable processes and excellent business services.
Practical advantages are clear: simple online incorporation, steady legal rules and high-quality infrastructure. These traits help with bank introductions, supplier deals and enterprise engagements.
Operationally, “pro-business” means transparent fees, fast registration steps and an ecosystem of corporate services that support non-resident directors and shareholders.
Tax and tidy reporting
Tax competitiveness depends on clean bookkeeping, correct filings and timely returns. Good accounting turns tax efficiency into a compliance outcome, not a marketing claim.
Common blind spots and regulated risks
- Assuming a virtual setup removes registered office obligations — it does not.
- Underestimating KYC and bank onboarding delays can stall operations.
- Treating directors or secretaries as paper roles risks penalties from authorities.
- Certain regulated activities need licences and GST registration where thresholds apply.
- Employment rules, IP protection and import/export checks pose ongoing operational risks across years.
Bottom line: choosing this base is straightforward; staying compliant across months and years protects your company, directors and reputation.
Pre-incorporation essentials: structures, eligibility, and planning
Deciding the right legal vehicle early saves time, money and operational headaches.
Choose the setup that fits control, liability and how you want banks and partners to see your group.
Which structure suits your business?
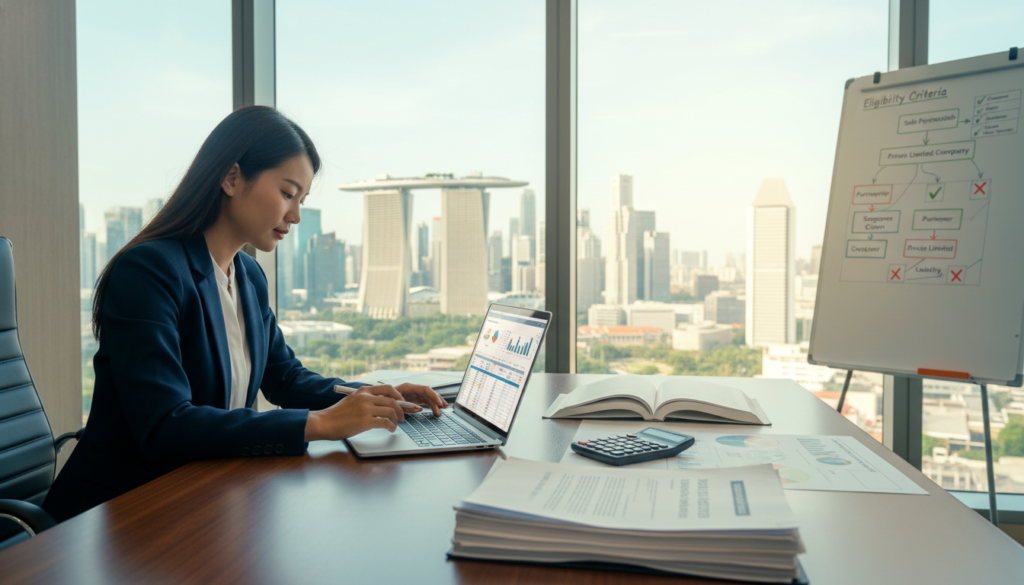
Common options are Private Limited (Pte Ltd), Subsidiary, Branch Office and Representative Office. A Pte Ltd is a separate legal entity with limited liability and higher credibility with banks.
Branch Offices mirror the parent and expose the parent to local liabilities. Representative Offices only do non‑revenue work and have strict headcount and eligibility limits.
Shareholders and capital basics
Foreign owners may hold 100% of shares. Minimum issued capital can start at S$1.
Paid-up capital becomes official once funds are deposited and lodged with authorities.
Directors and the ordinarily resident rule
Every entity must appoint at least one director who is ordinarily resident. Options include a local director, a nominee arrangement or appointing an eligible pass holder.
Directors must have legal capacity and not be undischarged bankrupts.
Registered filing agents and office rules
Foreign applicants must use a licensed registered filing agent. Regulated agents reduce rejection risk and align structure with licences and filings.
The registered office must be operational during office hours, accept mail and cannot be a P.O. Box. Using corporate services for an address helps avoid missed notices.
| Structure | Control & Liability | Tax & Banking |
|---|---|---|
| Private Limited (Pte Ltd) | Separate legal entity; limited liability | Preferred by banks; clearer tax residency |
| Subsidiary | Parent owns shares; limited liability at subsidiary level | Independent filings; distinct tax position |
| Branch Office | Extension of parent; parent liable | Banking may treat as non‑resident branch; simpler reporting alignment |
| Representative Office | No separate legal identity; no trading | Not revenue earning; limited banking services |
Singapore company compliance for foreigners: incorporation steps and documentation
Begin with a short checklist—name options, SSIC codes and certified identity documents—to speed registration.
Typical workflow with a registered filing agent follows a simple path:
- Pre-checks and activity code selection (SSIC).
- Name application and reservation.
- KYC collection and certification.
- Constitution adoption and statutory appointments.
- ACRA submission and issuance of e‑confirmation.
KYC checklist for foreign directors and shareholders
Provide a certified true copy of the passport photo page and a proof of address dated within three months.
Certification must be by an authorised person; uncertified scans often cause delays.
Name reservation, fees and referral delays
Name application is a government S$15 fee; registration is S$300. Reserve a name early — noted windows vary (60–120 days) and some names are referred to authorities (e.g., education bodies), which can extend to 14–60 days.
SSIC codes and timeline expectations
Choose primary and secondary SSIC codes that reflect real activities to avoid future licensing or banking checks.
With complete documents, registration can take about 0.5–1 business day; complex or referred cases can stretch to around two weeks.
| Item | Fee / Time | Note |
|---|---|---|
| Name application | S$15 | Reservation window: 60–120 days |
| Registration | S$300 | E‑confirmation issued on successful filing |
| Referral delays | 14–60 days | Restricted terms or regulated activities |
“Complete paperwork is the single biggest factor that speeds an incorporation.”
Immediate post-incorporation compliance you must not miss
Start strong: the first weeks after incorporation set the tone for regulatory rhythm and operational hygiene. Tackle day‑one tasks quickly and schedule the next steps across the first six months to avoid compounding risk.
Appoint a company secretary within six months
Under the Companies Act a company must appoint a company secretary within six months of registration. Directors remain responsible for choosing a competent secretary who can meet statutory duties.
A good secretary keeps registers, prepares resolutions, tracks filing deadlines and handles official notices. Outsourced corporate services often supply this expertise for foreign-run setups.
Opening corporate bank accounts: documents and resolutions
Prepare documentation early. Banks typically request:
- ACRA incorporation confirmation and Business Profile
- Constitutional documents (M&AA/constitution), certified
- Proof of address and ID for signatories and beneficial owners
- A signed board resolution authorising account opening
Align SSIC activity, KYC details and transaction intent to reduce delays. Incomplete or inconsistent documents often stall onboarding.
When to plan Employment Pass or EntrePass applications
If founders need to relocate, manage an office or replace a nominee director, apply for an employment pass early. An appropriate permit also eases hiring and employee management.
“Complete paperwork is the single biggest factor that speeds an incorporation.”
Annual statutory compliance calendar with ACRA and IRAS
An effective timetable links your financial year‑end with AGM dates, Annual Return filing and tax submissions.
Setting your FYE and why the date matters
Choosing a year‑end date affects reporting workload and potential incentives. Align the FYE with group reporting cycles to reduce reconciliation work.
New‑company tax relief eligibility can depend on the first three consecutive years after incorporation. Pick an end‑date that helps demonstrate qualifying income periods.
AGM obligations and timing
A company must hold an AGM once every year. The meeting must occur within 15 months of the previous AGM and generally within six months of the FYE.
Annual Return deadlines
Listed entities file Annual Returns within five months after the FYE. Non‑listed companies have seven months to complete filing. Do not wait until the last week to submit.
IRAS Estimated Chargeable Income (ECI)
Submit the ECI within three months of the FYE. This supports provisional tax assessment and avoids surprises at year‑end.
“Build a clear annual calendar: FYE → accounts → AGM → Annual Return → ECI.”
- Keep month‑end accounting tidy to reduce last‑minute corrections.
- Track GST dates if registration thresholds apply.
Accounting, audit, and tax compliance requirements for foreign-run businesses
Sound financial controls and timely record-keeping are the backbone of any cross-border business. Keep accounts up to date each month to reduce last-minute corrections and IRAS queries.
When an audit is required
An auditor must be appointed within three months of incorporation unless the entity is exempt. Auditors will test revenue recognition, expense substantiation, intercompany charges and payroll items.
Audit readiness is year‑round work. Monthly closes, supporting invoices and reconciliations make the audit faster and cheaper.
Small Company Concept and small group rules
Audit exemption applies when a business meets two of three thresholds: turnover ≤ S$10 million, total assets ≤ S$10 million, and employees ≤ 50.
Groups can qualify as a small group using consolidated figures under the same two‑of‑three test.
Reporting framework: SFRS vs SFRS for Small Entities
SFRS aligns with IFRS; SFRS for Small Entities offers simpler disclosures for non‑publicly accountable firms. Choose the simpler standard if you expect modest growth, but note lenders and investors may prefer full SFRS.
Tax, GST and practical filing controls
Track turnover, deductible expenses, intercompany invoices and payroll throughout the year. Keep GST classification and invoices consistent with SSIC activity to avoid mismatches.
Late lodgements can incur penalties (up to S$600 for annual filings) and persistent tax non‑filing risks court action and larger fines. Directors should prioritise statutory calendars and use experienced corporate services to manage filing deadlines.
| Area | Key action | Why it matters |
|---|---|---|
| Audit | Appoint auditor within 3 months (unless exempt) | Avoids delays and director exposure |
| Small company test | Apply 2-of-3 thresholds (turnover/assets/employees) | Determines audit exemption |
| Reporting | Choose SFRS or SFRS for Small Entities | Impacts disclosures, lenders and investors |
| Tax & GST | Monthly tracking of revenue, expenses, GST | Reduces IRAS queries and filing risk |
“Monthly routines and clear approval matrices reduce audit friction and tax risk.”
Conclusion
,
A resilient incorporation starts when you map duties, dates and roles into a simple operating rhythm.
Treat compliance as an operating system that spans incorporation, statutory appointments, filings and tax reporting. This approach makes the business easier to run and less prone to surprises.
Non‑negotiables include engaging a licensed filing agent, maintaining a functioning registered office, appointing at least one ordinarily resident director and naming a company secretary within the required months under the Companies Act.
Set a clear annual cadence: choose an FYE that suits your group, keep accounts current, prepare early for AGM and Annual Return filing, and submit the IRAS ECI on time to reduce penalties.
Audit your status now: check the name records, office arrangements, statutory registers and tax calendar. If gaps appear, engage experienced corporate services to close them quickly and keep the business steady through the year.
FAQ
What makes Singapore a pro-business base for overseas founders?
What are common compliance risks that overseas owners often miss?
Which business structures should I consider before incorporation?
Can foreigners hold 100% of share capital?
Why must a company have a director who is ordinarily resident locally?
Do foreigners need a registered filing agent to incorporate?
What are the rules for a registered office address?
Which documents are required for KYC checks during incorporation?
How do name reservation rules and common delays work?
How do I select appropriate SSIC codes for my activities?
What incorporation timelines and fees should I budget for?
What must be done immediately after incorporation?
What documents are typically needed to open a corporate bank account?
When should founders apply for Employment Pass or EntrePass?
How do I set the financial year end and why does it matter?
What are the Annual General Meeting and annual return obligations?
When must estimated chargeable income be submitted to IRAS?
When is an audit required and how do auditor appointments work?
What is the Small Company Concept audit exemption?
Which reporting frameworks are applicable and how do I choose?
What are corporate tax fundamentals to track through the year?
Dean Cheong is a Singapore-based B2B growth strategist and the CEO of VOffice. He helps companies scale revenue through sharper sales execution, CRM implementation, and go-to-market strategy, backed by a strong foundation in business banking and finance from Nanyang Technological University and a track record of driving sustainable, performance-led growth.